Publicis Buys LiveRamp for $2.5B All-Cash at $38.50/Share — 30% Premium and a $2.5M Retention Stack Buried in the 8-K
Publicis Groupe is acquiring LiveRamp (NYSE: RAMP) at $38.50/share — a 30% premium and a $2.5B all-cash deal. The 8-K also locks in $2.5M of executive retention pay.
A blue-chip global ad holding company just paid a 30% premium to take a US data-collaboration platform private. On May 18, 2026, LiveRamp Holdings, Inc. (NYSE: RAMP) filed an 8-K disclosing that Publicis Groupe SA will acquire the company for $38.50 per share in all-cash consideration, valuing LiveRamp at approximately $2.5 billion and representing a 30% premium to the May 15, 2026 closing price. Publicis filed the matching DEF 14A on the same day with an acquirer-side enterprise value of $2.2 billion and a 29.8% premium calculation.
Same-day, dual-side filings on a $2.5B ad-tech consolidation is the kind of disclosure pattern that gets a transaction priced into a stock before the market open. The 8-K also carries a second disclosure that does not make any of the deal-day headlines: a $2.5 million pool of cash retention awards for four LiveRamp executives.
What NexusAlert Surfaced on Filing Day
The two filings hit the alerts feed paired as the same-day dual-side detection — the Publicis DEF 14A and the LiveRamp 8-K rendered as adjacent rows in the High-severity queue, with the deal economics already extracted into the summary column.
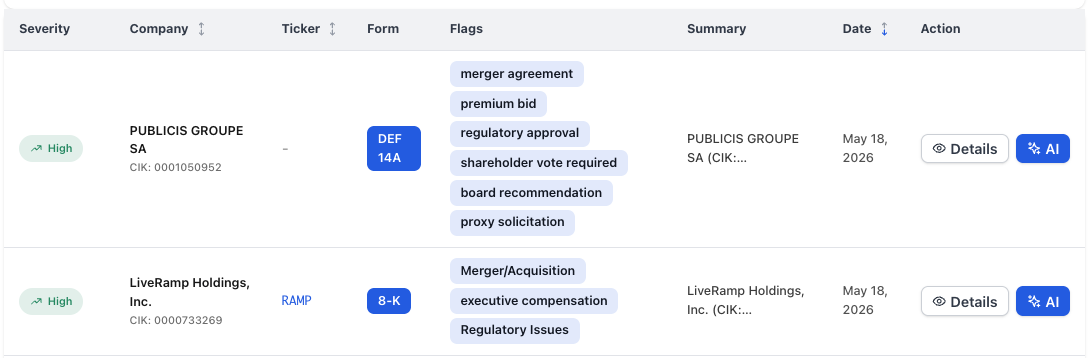
Two rows, two CIKs, one transaction. A subscriber watching either side of the deal on a NexusAlert watchlist got the full pairing in a single view — without having to manually correlate the acquirer’s proxy solicitation with the target’s 8-K disclosure.
What the LiveRamp 8-K Discloses
- Acquirer: Publicis Groupe SA (Paris-listed, parent of Epsilon, Sapient, and the broader Publicis Media network).
- Consideration: $38.50 per share in cash, all-cash transaction.
- Implied equity value: approximately $2.5 billion.
- Premium: 30% to the May 15, 2026 close, the last trading session before the announcement.
- Concurrent Q4 FY26 results: total revenue of $206 million, up 9% year-over-year; non-GAAP diluted EPS of $0.52.
- Retention awards: $2.5 million in cash awards to four key LiveRamp executives, payable on closing or on qualifying terminations.
- Severity classification: High / Opportunity. Flags in the Alert Details modal: M&A, executive compensation, litigation. (The same alert rolls up to Regulatory Issues in the daily summary table.)
The Publicis DEF 14A files the deal under a $2.2 billion total enterprise value with the same $38.50/share number and a 29.8% premium calculation. The gap between $2.2B (acquirer-side EV) and $2.5B (target-side equity value) is the standard cash-and-debt adjustment, not a discrepancy: Publicis is reporting EV net of assumed cash; LiveRamp is reporting equity value gross.
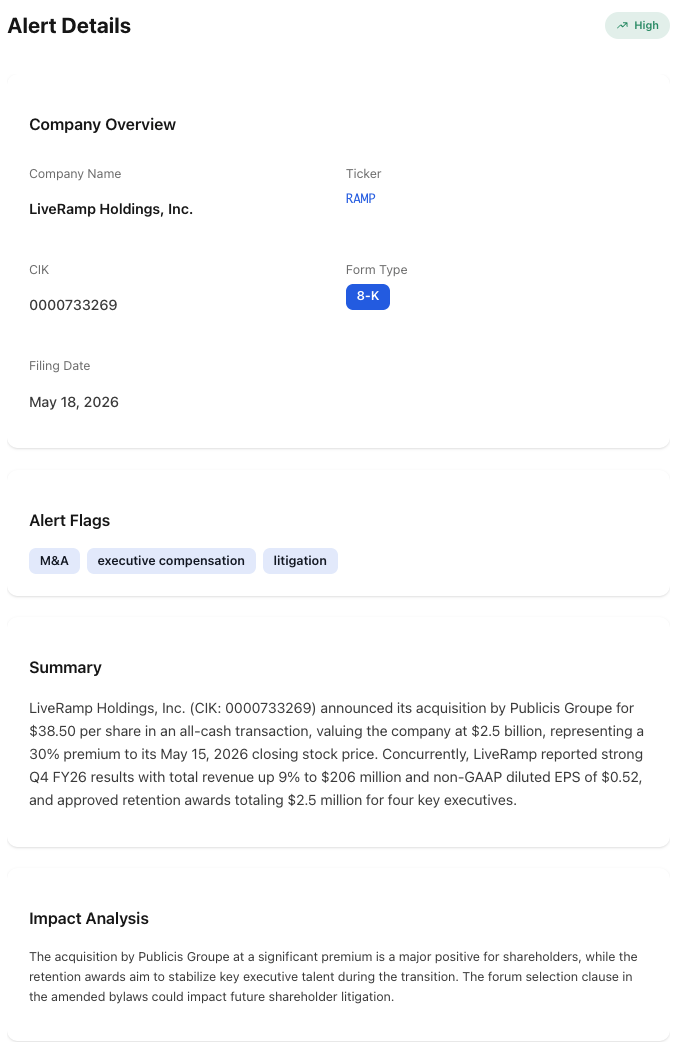
The Alert Details panel does the first-pass synthesis: company, ticker, form, severity, the flag stack, and the AI summary that pulls the deal economics and the retention pool out of the 8-K body in one view. The litigation flag is the platform’s read on the executive-compensation disclosure being the kind of provision that frequently attracts post-merger litigation — not a separate lawsuit.
Why a 30% Premium on RAMP Is the Number That Sets the Read
LiveRamp had spent most of 2025 and the first half of 2026 trading in the high-$20s. A $38.50 bid against a $29.60 reference price is not a polite premium — it is the kind of bid that says the acquirer wanted no holdout shareholders and no contested vote.
- Premium-to-VWAP is the deal-table number. 30% to a single-day close is meaningful; on a 30-day VWAP basis the premium is higher still, because RAMP had drifted lower through late April and early May.
- All-cash, not stock. Ad-tech roll-ups frequently use stock or cash-and-stock to preserve acquirer balance sheets. Publicis paying entirely in cash is a balance-sheet decision: the company has the financing capacity and would rather not dilute its own equity at current Paris-listed valuations.
- No collar, no break-up financing. All-cash deals without a financing condition close faster than mixed-consideration deals. Publicis is signaling that regulatory approval — not financing — is the only meaningful gating item.
The 30% number is the share-price story. The retention pool and the Q4 print are the structural story.
$2.5M of Retention Awards Is the Detail Most Deal Coverage Will Miss
The 8-K discloses $2.5 million in cash retention awards for four LiveRamp executives. That is the standard “Section 4980G change-in-control parachute” mechanism that protects an acquirer’s transition team from walking immediately post-close.
- Retention pools are pre-priced into the deal. A $2.5M retention pool on a $2.5B acquisition is 0.1% of equity value — a rounding error to Publicis, but a material personal economics shift for the four covered executives.
- The pool is small because the equity is large. LiveRamp executives already hold significant unvested RSU and PSU positions that will accelerate on a change-of-control. The cash retention pool is a top-up — it covers the gap between equity acceleration and the value of continued employment for the integration period.
- Four named executives — not the CEO. Retention pools concentrated below the C-suite tell you Publicis cares most about preserving the operating layer that runs LiveRamp’s data infrastructure, not the deal-signing leadership.
The fact that this was filed in the same 8-K as the deal announcement rather than in a follow-on 8-K is the deliberate disclosure choice. It puts the parachute disclosure inside the high-traffic deal filing, which technically improves disclosure quality even though it gets buried by the headline economics.
Why Publicis Is Paying $2.5B for a Data-Collaboration Platform
LiveRamp’s core business is identity resolution and data collaboration — the infrastructure that lets advertisers and publishers match first-party data sets without exposing the underlying records. That capability is the operating layer for the AI-agent-driven ad targeting that Publicis flagged in its DEF 14A as a strategic priority.
- Data co-creation for AI agents. Publicis’s DEF 14A explicitly cites LiveRamp’s data collaboration capabilities as the input layer for AI agent-driven media buying. The pitch is that an AI agent that buys media on behalf of a brand needs a privacy-safe identity layer to target effectively — and LiveRamp owns one of the few production-grade identity layers at advertising-industry scale.
- Year-one accretive. The DEF 14A flags the deal as accretive from year one of consolidation. That is unusual for a 30%-premium acquisition; most premium deals are EPS-dilutive for two-to-three years before synergies kick in.
- Lifts 2027-2028 net-revenue and headline-EPS objectives. Publicis is telegraphing that the deal expands the multi-year growth algorithm — not just the next-quarter print.
A 30% premium, all-cash, year-one accretive, with a small retention pool concentrated below the C-suite. That combination only makes sense if the acquirer thinks the target is undervalued at the screen and the integration risk is small.
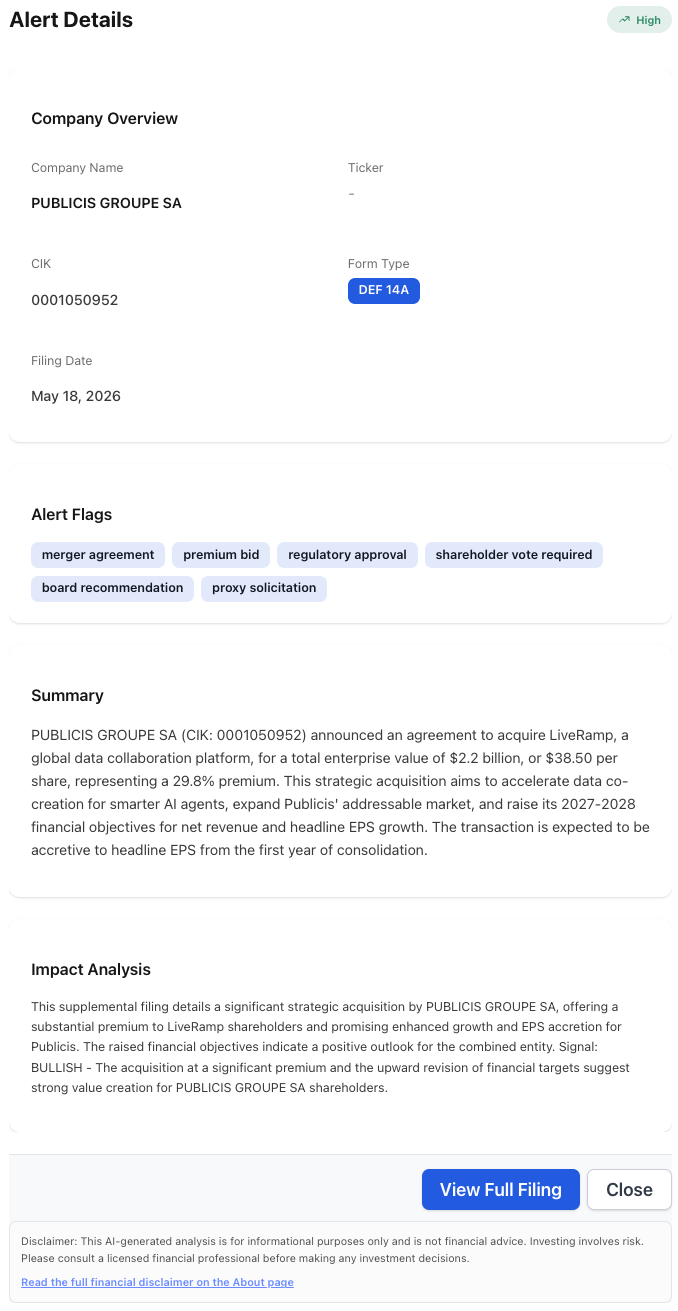
The acquirer-side Alert Details panel is the read most deal coverage doesn’t print. The AI Impact Analysis explicitly tags the signal as BULLISH for Publicis shareholders — significant premium plus raised financial objectives plus year-one EPS accretion. That is the unusual combination: acquirers paying premiums for synergies usually take a multi-quarter EPS hit before the math turns positive. Publicis is telling the market the math turns positive immediately.
Why the Concurrent Q4 Print Matters
LiveRamp announced Q4 FY26 results in the same 8-K as the merger agreement — a deliberate choice that puts the operating numbers in the same disclosure as the deal economics.
- Revenue up 9% to $206M. That’s a high-single-digit growth rate on a stabilized base — not the 20%+ growth of LiveRamp’s 2022-2023 peak, but not the contraction some ad-tech peers have reported in the same window.
- Non-GAAP diluted EPS of $0.52. Profitable on a non-GAAP basis at a high-single-digit growth rate is the profile that supports a 30% premium.
- The Q4 print pre-empts the “you sold at the bottom” critique. By publishing the operating results in the same filing as the deal, LiveRamp’s board can show the bid lands against a quarter of profitable growth, not against a deteriorating fundamentals story.
Who’s Already Long RAMP — the Institutional View
The $2.5B takeout did not land on an empty cap table. NexusAlert’s Investor Trends view for RAMP collapses the 13F running cumulative value and the SC 13D/13G ownership disclosures into a single chart, so you can read the institutional positioning history at a glance:
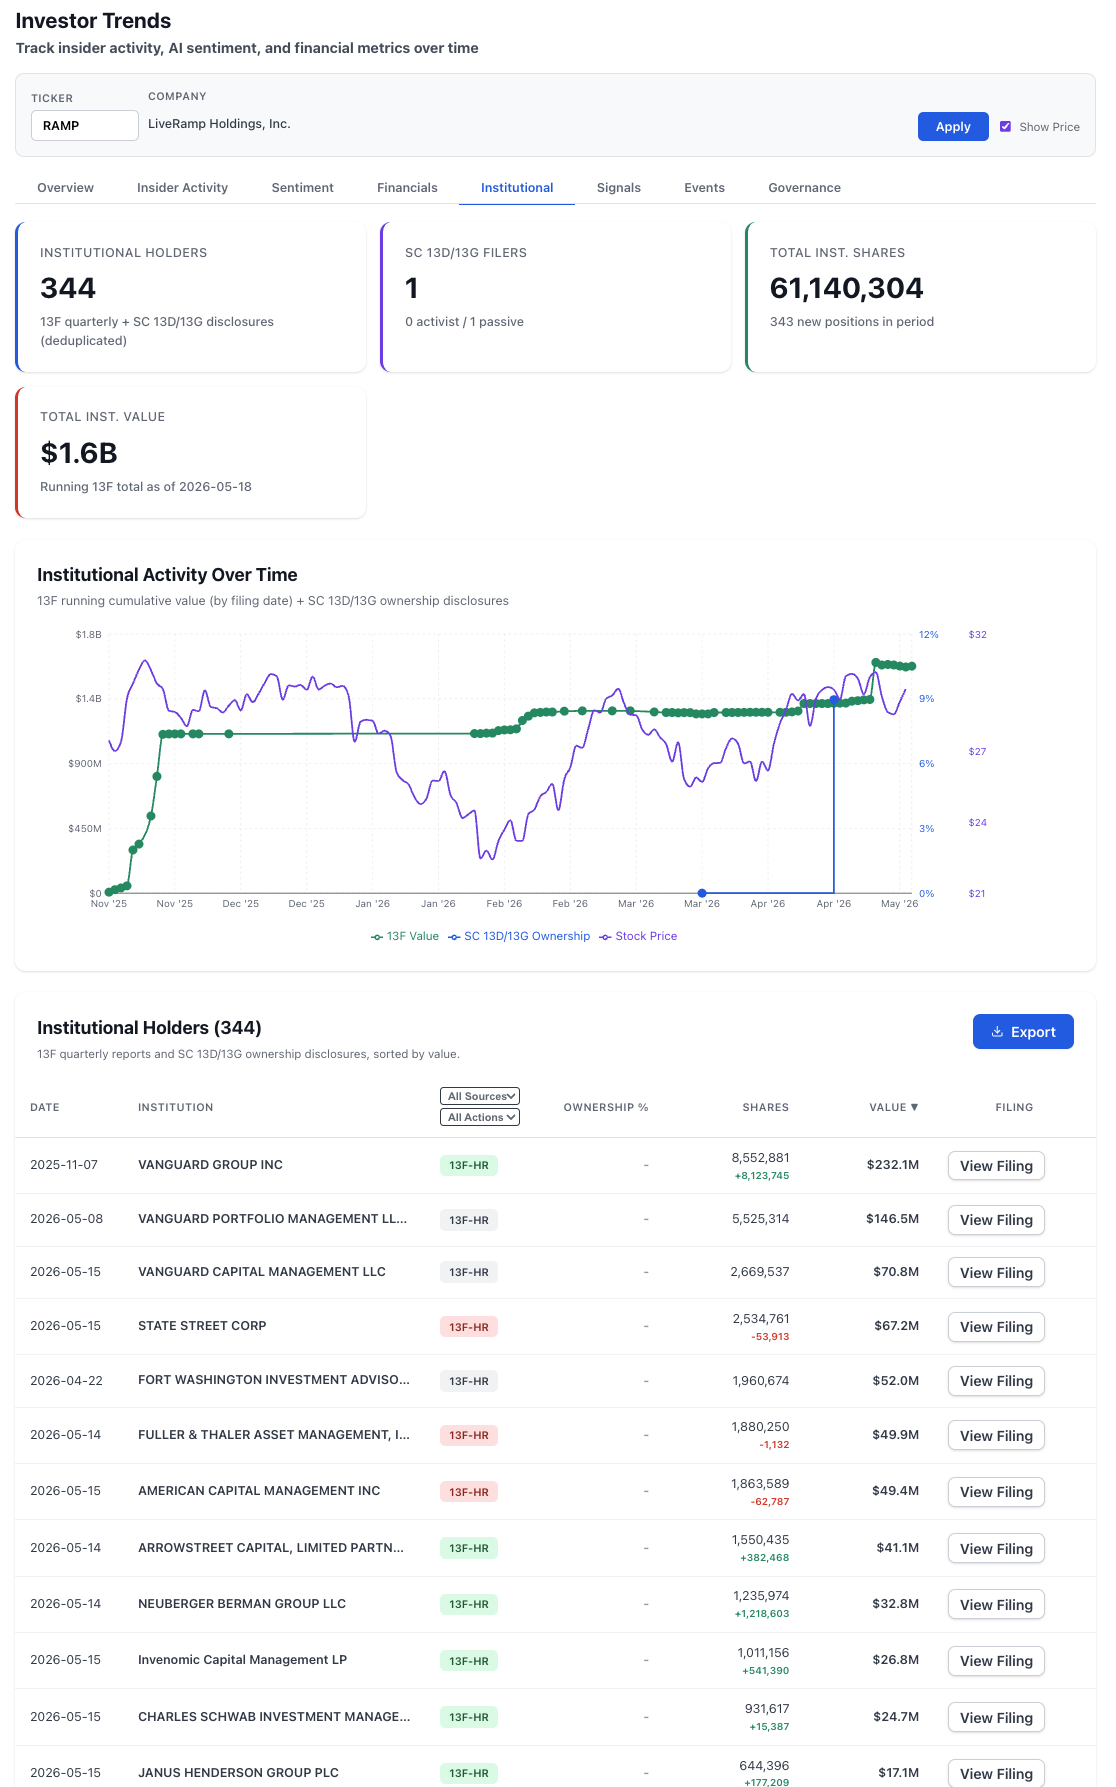
The structural read on the institutional side: 344 institutional holders, $1.6 billion of running 13F value, 343 new positions opened during the period, and a cumulative 13F line that went from near zero in November 2025 to roughly $1.6 billion by May 2026. Institutions were scaling into RAMP for six straight months ahead of the takeout.
A few patterns worth flagging from the holders table:
- Vanguard Group added 8,123,745 shares on November 7, 2025 to reach a top-ranked position of 8,552,881 shares ($232.1M). That is one of the largest single-quarter accumulation events on the table — and it happened six months before the deal announcement.
- Vanguard Portfolio Management added a 5,525,314-share position by May 8, 2026 ($146.5M), and Vanguard Capital Management added 2,669,537 shares on May 15, 2026 ($70.8M) — three Vanguard entities collectively crossing 16.7 million shares in the window.
- State Street holds 2,534,761 shares ($67.2M), trimmed 53,913 in the latest filing — index-tracker rebalancing rather than thesis change.
- Fort Washington Investment Advisors holds 1,960,674 shares ($52.0M) — a long-only mid-cap value buyer.
- Fuller & Thaler Asset Management holds 1,880,250 shares ($49.9M), down 1,132 — behavioral-finance specialist with a near-flat position.
- Arrowstreet Capital added 382,468 shares to reach 1,550,435 shares ($41.1M) — quant-overlay accumulation.
- Neuberger Berman added 1,218,603 shares to reach 1,235,974 ($32.8M) — a new institutional position taken in the immediate run-up to the deal.
The institutional accumulation across late 2025 and early 2026 looks structurally consistent with funds pre-positioning into an underpriced data-collaboration platform — and now harvesting that positioning at the $38.50 takeout. Vanguard’s 8.1M-share add in November 2025 is the single most visible “someone knew the floor was in” footprint on the table.
The flip side: an investor reading the Investor Trends view in real time over the last six months would have seen the wall of institutional buying without yet knowing what catalyst it was front-running. The platform shows the accumulation; the May 18 8-K reveals what the accumulation was for.
What’s Next
- Regulatory review. A $2.5B ad-tech acquisition in 2026 sits squarely in the antitrust focus area of every major regulator. Watch for HSR second-request activity in the US and any UK CMA / European Commission inquiry timelines disclosed in subsequent 8-K amendments.
- Shareholder vote. Publicis filed the DEF 14A — the proxy solicitation — on the same day. The shareholder vote date will be the next disclosure milestone; high-premium deals typically clear with 95%+ support.
- Closing-day 8-K. The transaction is expected to close inside 2026, with the exact close date to be disclosed in a subsequent 8-K. Watch for the change-in-control acceleration disclosures on closing day for LiveRamp’s executive equity.
- Retention-pool draws. The four named executives will draw from the $2.5M pool on closing or on qualifying terminations. Subsequent 8-K or proxy filings will disclose actual payments.
- Integration disclosures. Publicis’s first quarterly report post-close will include LiveRamp segment financials and any restructuring charges.
How NexusAlert Read This Filing
NexusAlert flagged both sides of the Publicis-LiveRamp deal as High-severity, opportunity-flagged alerts on May 18, 2026 — the LiveRamp 8-K with flags for M&A, executive compensation, and litigation (rolled up to Regulatory Issues in the daily summary), and the matching Publicis DEF 14A with flags for merger agreement, premium bid, regulatory approval, shareholder vote required, board recommendation, and proxy solicitation. Surfacing both sides of a cross-border M&A transaction on the same day — with the embedded $2.5M retention disclosure parsed out of the 8-K body and a BULLISH Impact Analysis on the acquirer — is the layered detection that makes the platform useful beyond simple deal-tracker tools.
The same-day pairing of an acquirer DEF 14A with a target 8-K is the cleanest read of “the deal is real and both sides have committed to disclosure.” Single-side filings frequently mean a leaked deal, an unsolicited bid, or an early-stage approach. Same-day dual filings mean a signed merger agreement with both legal teams ready to file simultaneously.
Layering the Investor Trends institutional view on top of the alerts gives the cap-table read: 344 holders, $1.6B of running 13F value, and a six-month accumulation arc through Q4 2025 and Q1 2026 that lined up almost perfectly with the takeout. The Filing Search + Alerts + Investor Trends combination is what turns “the deal was announced today” into “here’s who was already positioned, what the deal economics actually are, and what the AI Impact Analysis flagged about the acquirer’s read.”
Start Tracking Same-Day M&A Filings
Create a free NexusAlert account to get same-day alerts on 8-K merger announcements, DEF 14A proxy solicitations, premium bids, and the embedded retention-and-compensation disclosures that get buried in deal-day filings.
Sources
- Publicis to acquire LiveRamp to accelerate data co-creation for smarter agents — Yahoo Finance
- Publicis to acquire LiveRamp in $2.5 billion deal as ad-tech consolidation accelerates — Seeking Alpha
- LiveRamp Holdings, Inc. SEC filings — SEC EDGAR
- Publicis Groupe SA SEC filings — SEC EDGAR
- NexusAlert daily news-correlation report, May 18, 2026 — internal
Prefer to own it outright? NexusAlert lifetime access is available for a one-time payment of $299 — no subscription, no recurring charges, all future Pro features included. Learn more →