He's Buying the Company He Runs. His Own Board Made Him Pay 30% More for It.
Priority Technology CEO Thomas Priore is taking his own company private for $8.05 a share, a $1.6 billion deal. NexusAlert's Dossier shows the conflict of interest, and the check that reined it in.
He’s buying the company he runs. His own board made him pay more for it.
Priority Technology Holdings’ Chairman and CEO Thomas Priore is taking the payments company private for $8.05 a share in cash, a deal worth roughly $1.6 billion. He is the buyer. He also runs the company he is buying. $PRTH is a clean case study in why a CEO led buyout is one of the more loaded transactions in corporate finance.
The obvious read is that an insider used his position to grab the company cheap. The filing, and NexusAlert’s Company Dossier, tell a more specific story about the fight that happened before Priore got his price.
What the filing actually says
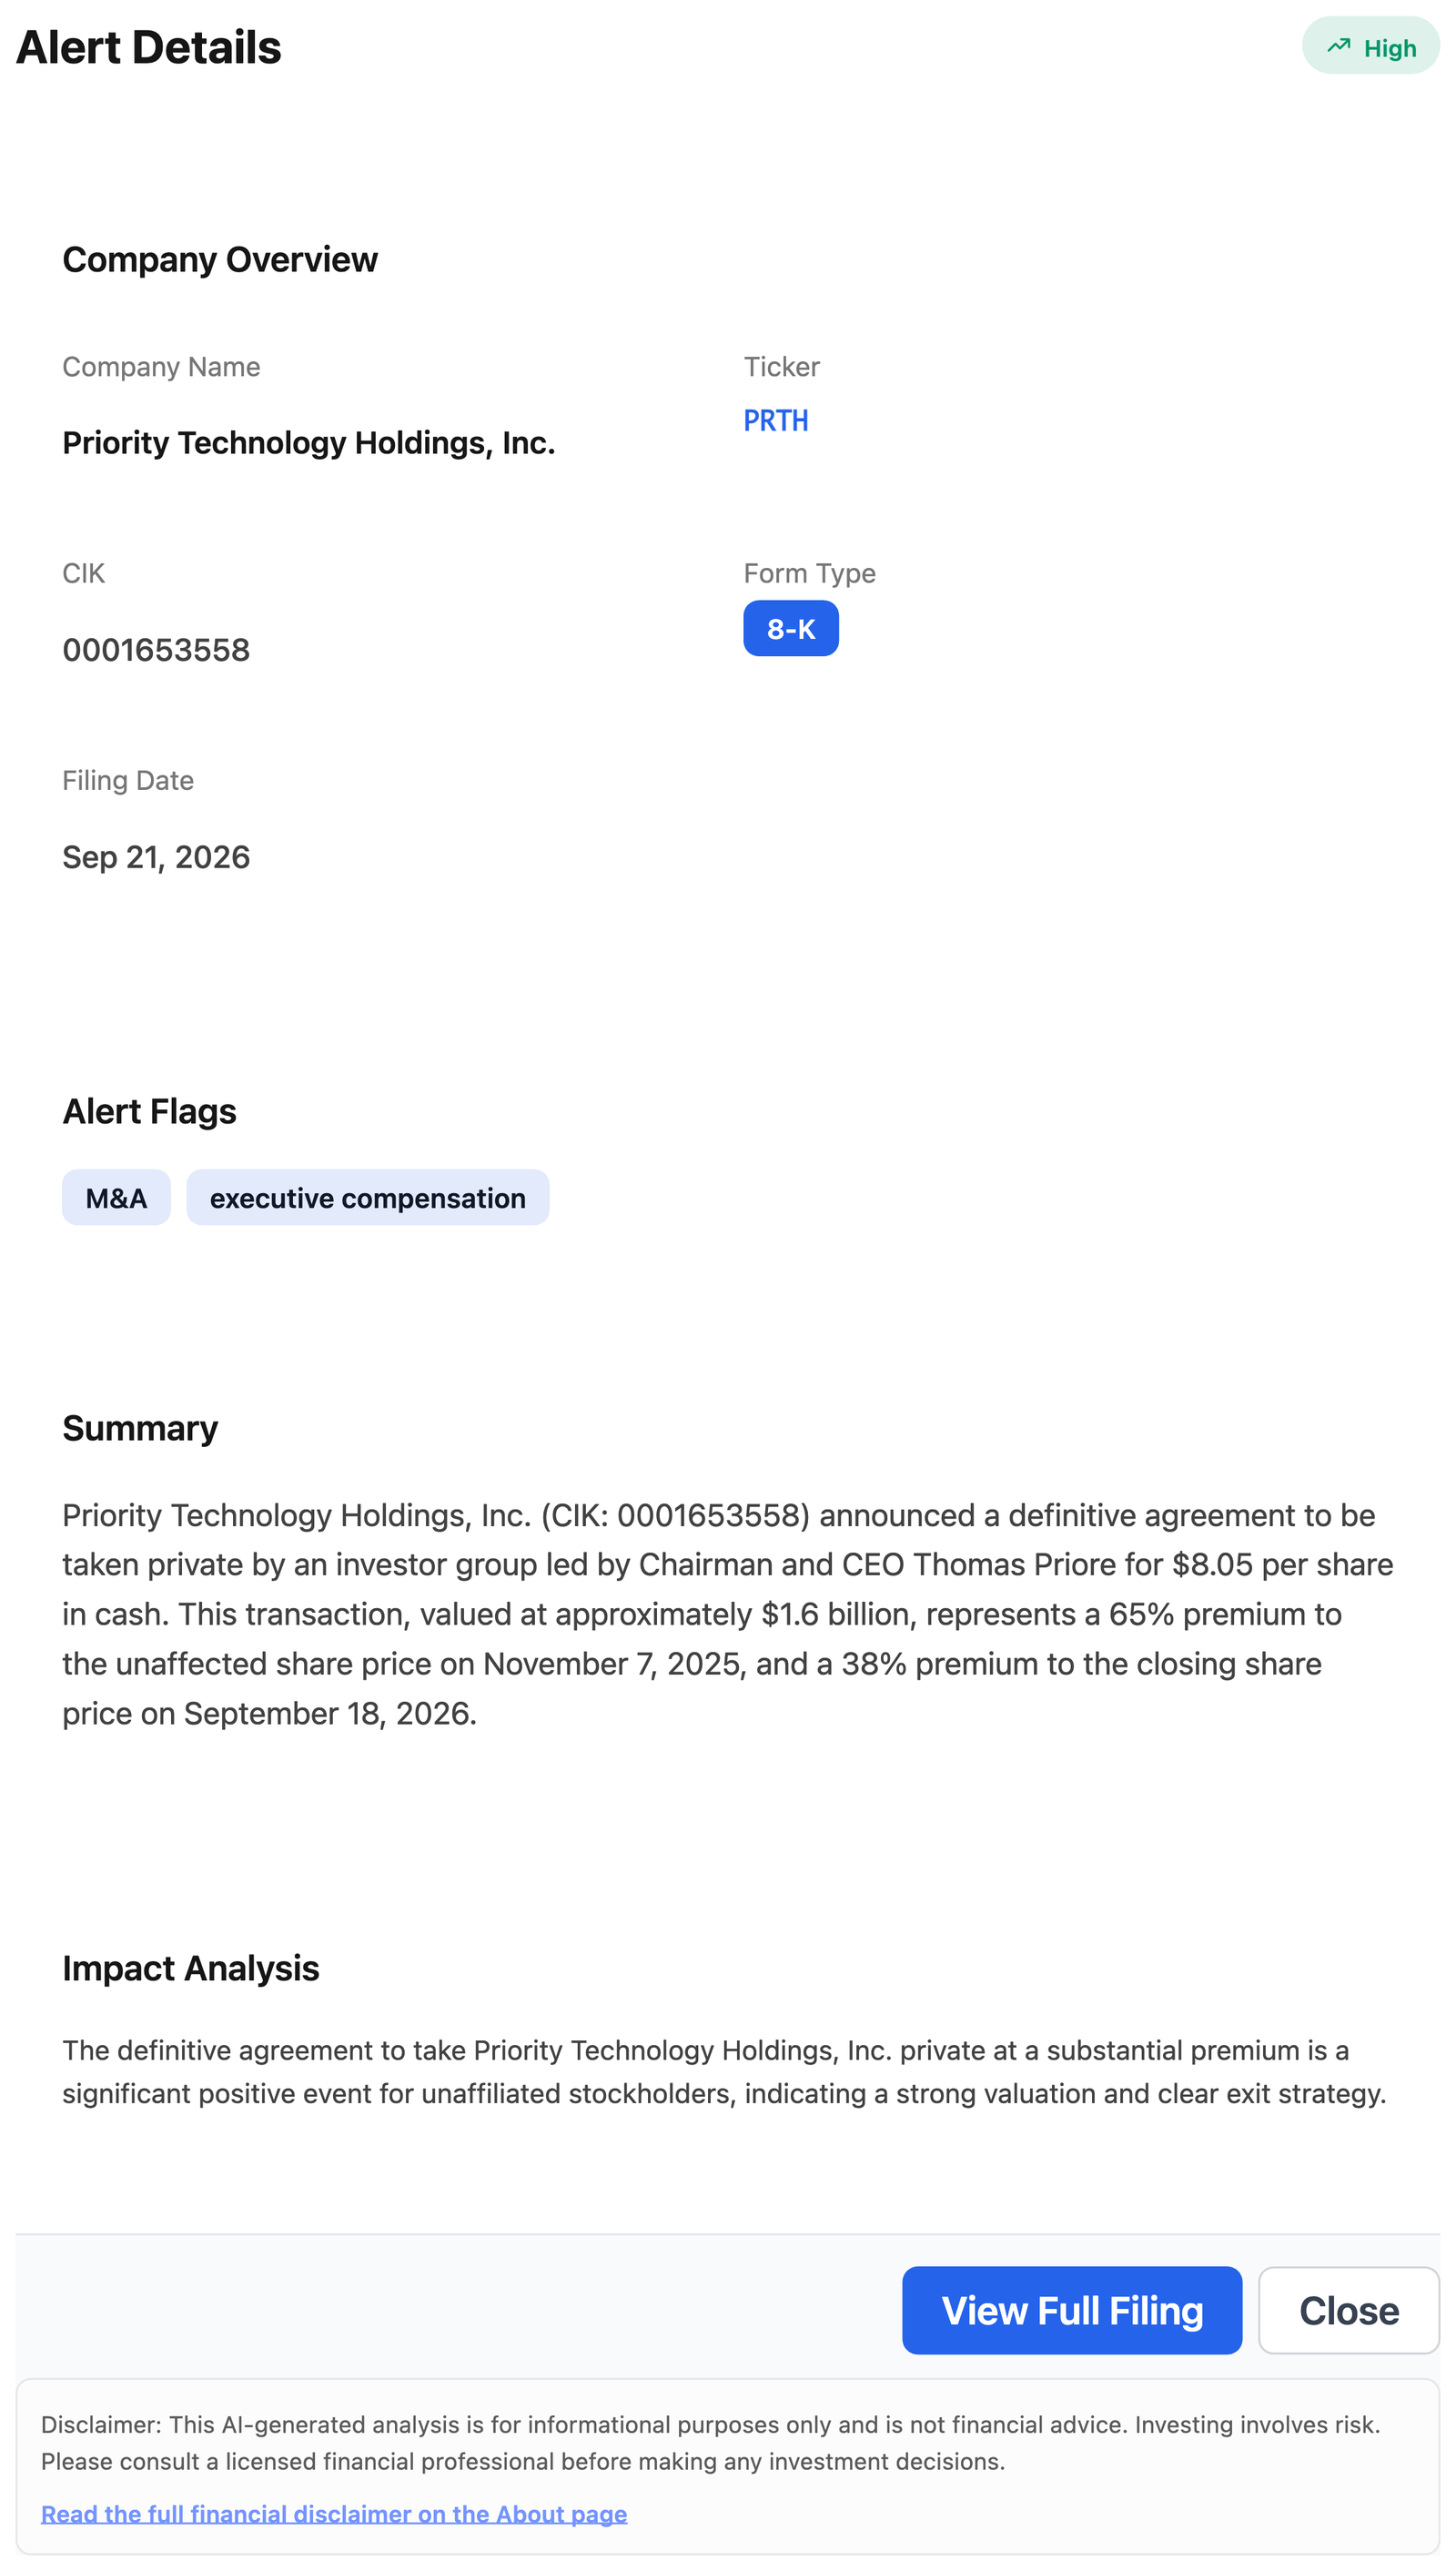
Priore’s investor group is paying $8.05 per share in cash for every share it does not already own, with equity commitments from funds advised by Searchlight Capital Partners helping finance the deal. The offer is 65% above Priority’s closing price on November 7, 2025, the last trading day before Priore’s initial proposal became public, and 38% above the September 18, 2026 close, the trading day right before the definitive agreement was announced.
Those two numbers only make sense read together. The 65% premium describes the whole run since the deal became known. The 38% premium describes what changed in the final stretch of negotiation, and that gap is where the real story sits.
Bust the misconception
A CEO led buyout looks, on its face, like the one person who knows the company best setting his own purchase price. That is not what the filing shows happened here. A special committee made up entirely of independent, disinterested directors reviewed Priore’s proposal, hired its own financial adviser and its own law firm, and negotiated the price up by more than 30% from Priore’s initial offer. The deal carries no financing conditions, and it still needs approval from a majority of shareholders who are not part of the buying group before it can close.
Priore did not set his own price. A committee that answers to every other shareholder did, and it moved the number by close to a third before it would sign off. That is the check that is supposed to exist in exactly this kind of transaction, and here it visibly did its job.
The bigger pattern
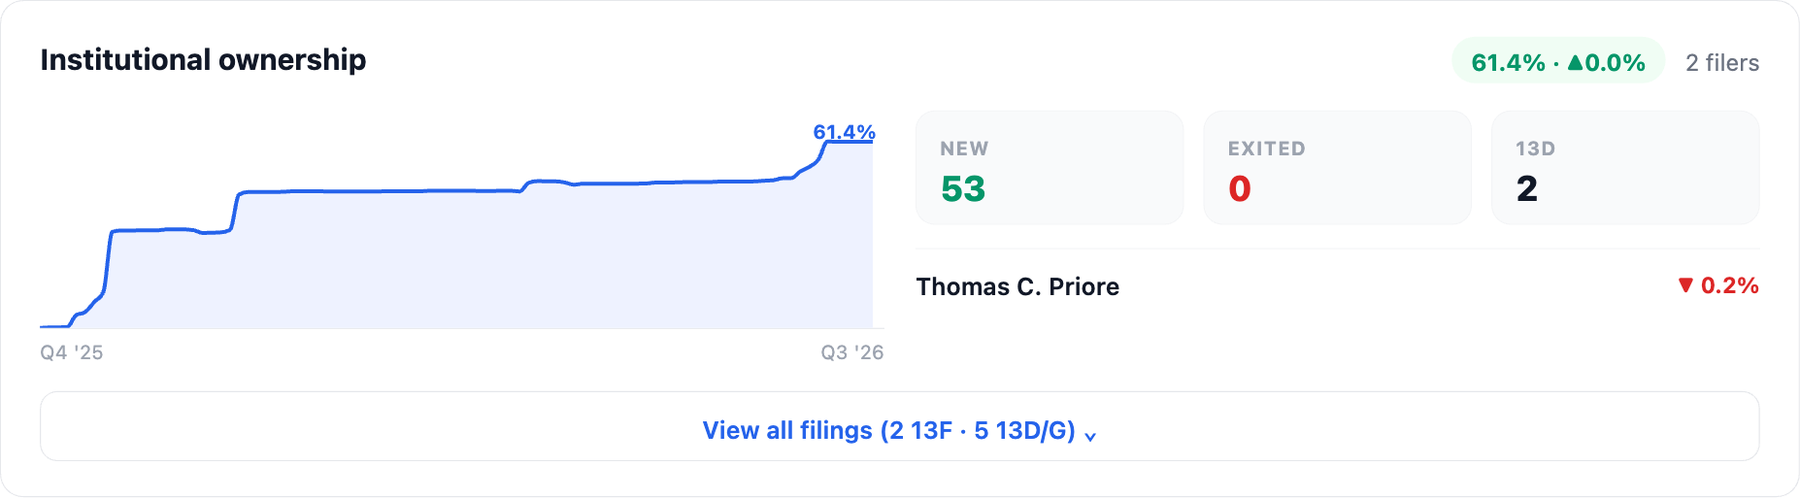
NexusAlert’s Company Dossier adds the layer a headline does not. The same filing that announces the buyout is paired with an SC 13D/A, and it is specific about who holds $PRTH today: Thomas Priore and other Supporting Stockholders collectively own approximately 61.4% of outstanding shares, and that whole block is rolling directly into the buying entity rather than cashing out. That is not outside institutional money backing the deal. It is the insider group’s own stake, already large enough on its own to make this buyout close to a formality once the independent vote clears.
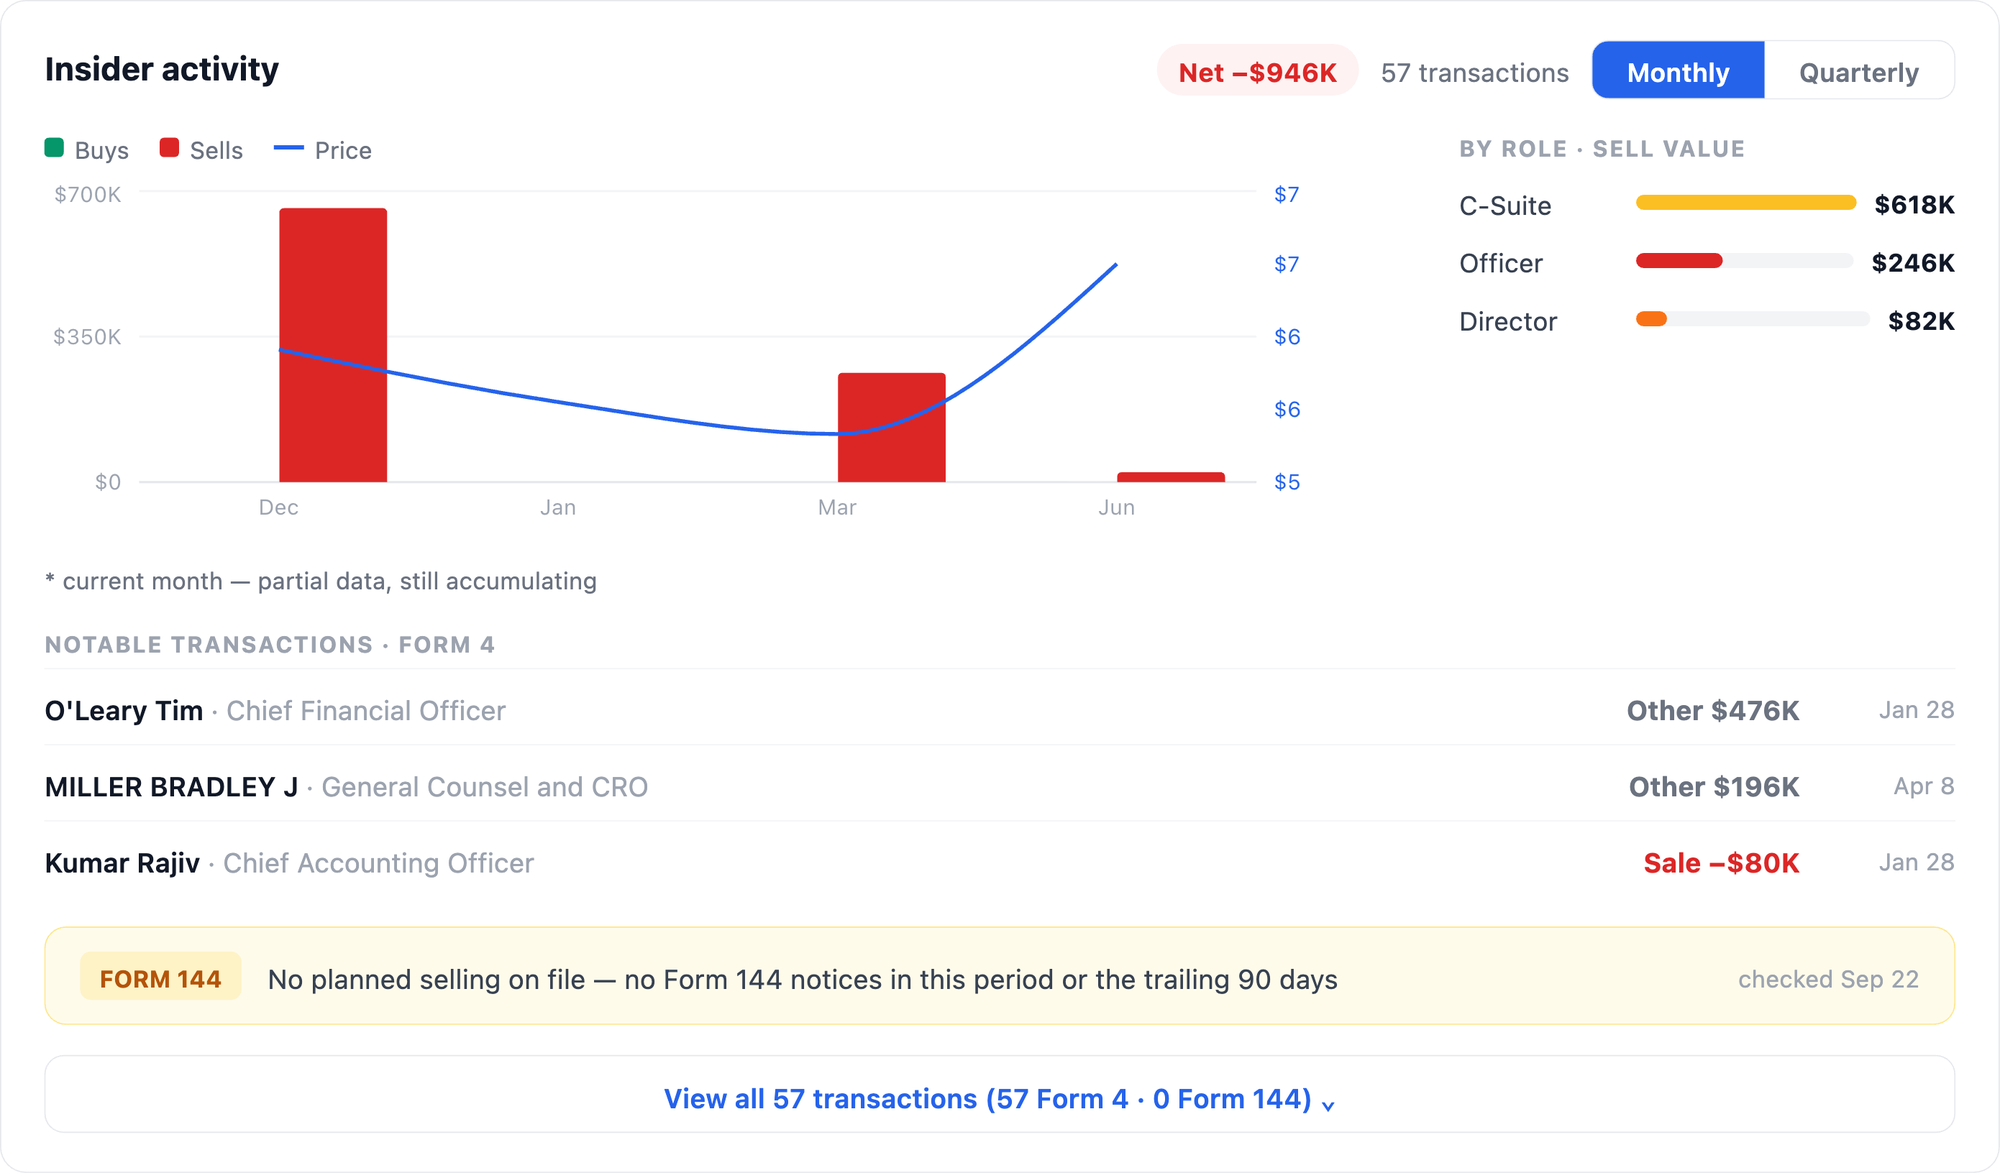
The Dossier’s insider activity chart adds one more texture. Over the trailing year, $PRTH insiders show net selling of $946,000 across 57 Form 4 filings, split roughly $618,000 from C-suite executives, $246,000 from other officers, and $82,000 from directors. That activity predates the buyout announcement by months, so it is not evidence anyone timed a sale around this deal. It is exactly the kind of pattern NexusAlert surfaces automatically though: a company where insiders had been trimming positions, while two of the five NexusAlert Company Scores sit in the bottom third, Insider Conviction at 3.8 out of 10 and Financial Strength at 3.6, even as Governance comes in above average at 6.0.
The person buying the company is not the one you should be watching. The people who negotiated against him are.
What to watch
The lesson here generalizes past payments companies. Any time an insider proposes to buy out the shareholders he already works for, the premium in the headline is the least useful number in the release. The number that actually tells you whether the deal is fair is what the independent committee extracted from the first offer, and whether the vote that has to approve it genuinely excludes the buyer’s own shares.
Priority Technology’s remaining shareholders still have to approve the deal, alongside the usual regulatory sign offs, before it can close in the first half of 2027 and the stock delists from Nasdaq. NexusAlert flagged the 8-K, the DEF 14A, and the SC 13D/A the same day they landed, and will keep tracking every filing between now and the vote. Read the whole filing, not just the premium in the first paragraph.
Create a free NexusAlert account
Sources
- Priority Technology Holdings Announces $1.6 Billion Take-Private Agreement at $8.05 Per Share (Yahoo Finance)
- Priority Technology Holdings, Inc. Announces Definitive Agreement with Investor Group Led by Chairman and CEO Thomas Priore to Take Company Private (Business Wire)
- A roughly $1.6 billion deal could take Priority Technology private. Shareholders would get $8.05 a share. (StockTitan)
- Priority Technology to go private in $1.6 billion CEO led deal (Pulse2)
Prefer to own it outright? NexusAlert lifetime access is available for a one-time payment of $299 — no subscription, no recurring charges, all future Pro features included. Learn more →