Three Filings. One Deal Day. Two Tickers. MARA's $1.52B Long Ridge Acquisition Lands in 8-Ks From Both Sides — and a 10-Flag Proxy.
On April 30, 2026, MARA Holdings filed an 8-K to acquire FTAI Infrastructure's Long Ridge Energy ($1.52B, 505 MW Hannibal, Ohio) and a DEF 14A responding to last year's failed say-on-pay vote. Seller FTAI filed its own 8-K confirming the divestiture. Three filings, two tickers, one trading day.
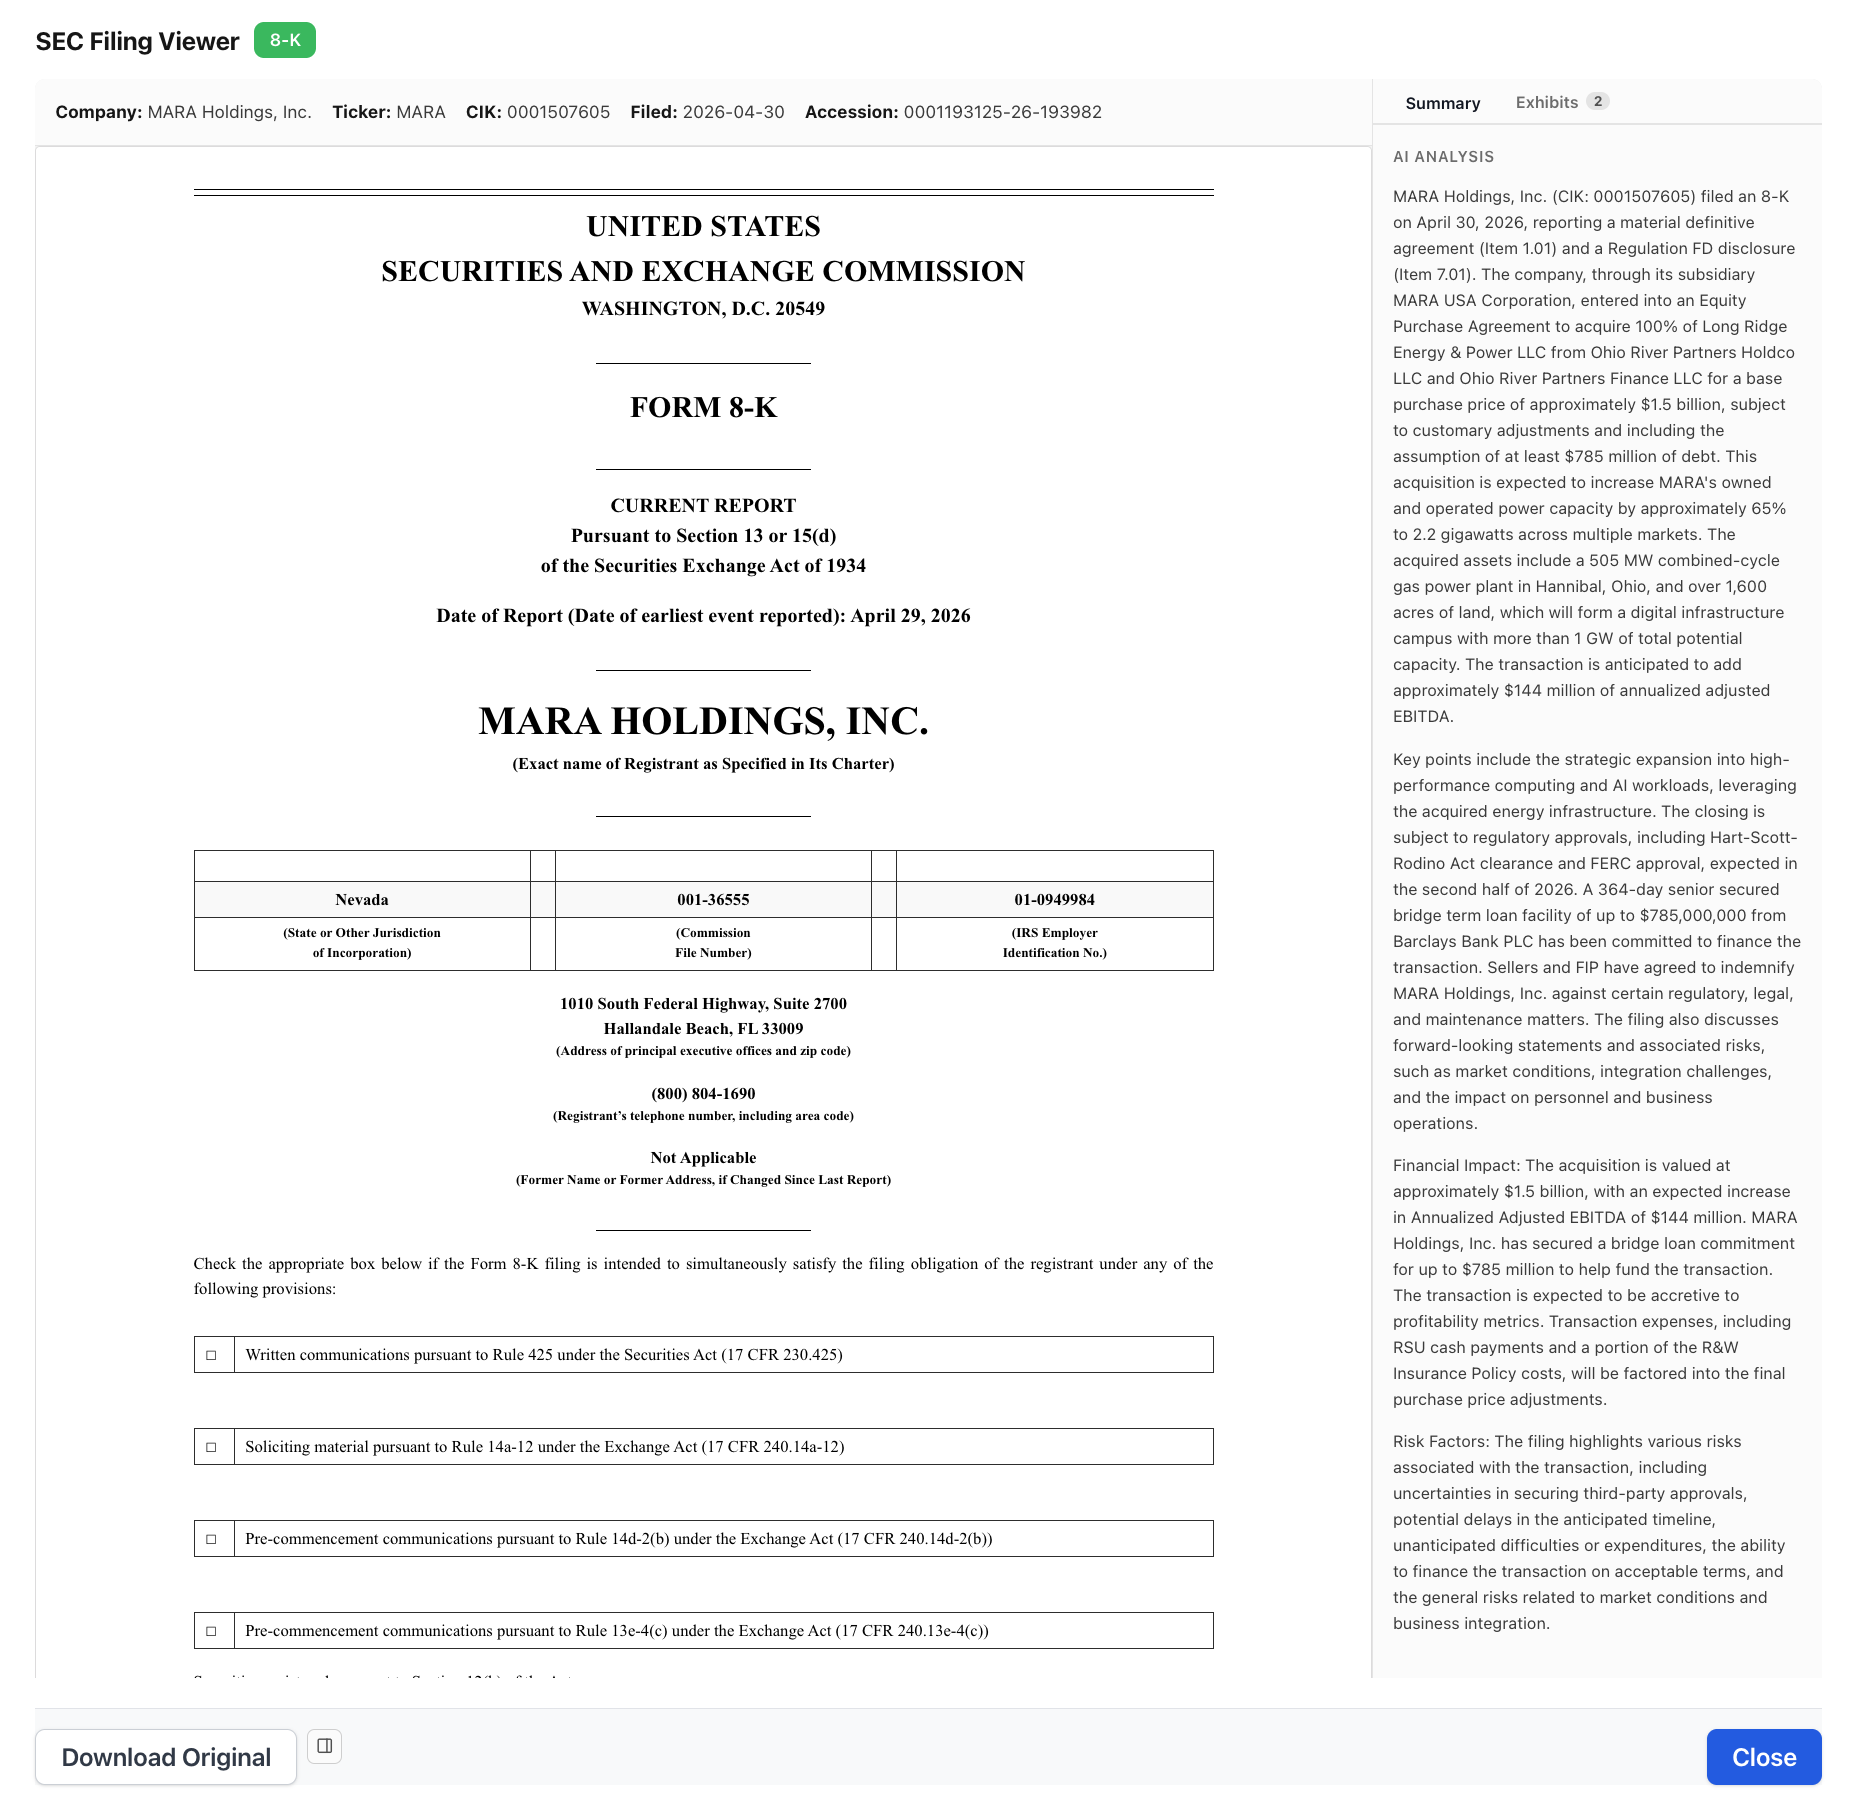
The cleanest way to read what happened at MARA Holdings on April 30, 2026 is not to read one filing — it is to read three, in order, on the same EDGAR timestamps. MARA Holdings, Inc. (NASDAQ: MARA) filed an 8-K disclosing a definitive agreement to acquire Long Ridge Energy & Power LLC for a base purchase price of approximately $1.5 billion (a total transaction value of approximately $1.52 billion including assumed debt), with the assumption of at least $785 million of debt. Minutes later, MARA filed a DEF 14A proxy — its first since a 2025 say-on-pay vote that received only ~21.6% support — describing a compensation overhaul, a request for 18 million additional plan shares, and a related-party arrangement with semiconductor designer Auradine, Inc. that has grown to $85.4 million invested plus $136.7 million in advanced product-purchase payments in 2025. On the seller side of the same transaction, FTAI Infrastructure Inc. (NASDAQ: FIP) filed its own 8-K confirming the divestiture of Long Ridge Energy, with closing expected in Q3 2026.
One filing reframes MARA’s asset base. The second reframes its equity story. The third confirms the seller has handed off a wholly-owned subsidiary at a $1.52B mark. Read together, they describe a different MARA than the bitcoin miner the ticker priced the morning before — and a different FTAI Infrastructure than the diversified-portfolio holdco it traded as the day before.
The 8-K Numbers That Reposition the Asset Base
The 8-K and the matching coverage from CoinDesk, Yahoo Finance, and Power Technology line up on the same fact set:
- Buyer: MARA USA Corporation (a wholly owned subsidiary of MARA Holdings, Inc.)
- Seller: FTAI Infrastructure Inc. (NASDAQ:
FIP), divesting wholly-owned subsidiary Long Ridge Energy & Power LLC, held through Ohio River Partners Holdco LLC and Ohio River Partners Finance LLC - Base purchase price: approximately $1.5 billion, subject to customary adjustments
- Total transaction value: approximately $1.52 billion (per FTAI Infrastructure’s matching 8-K), inclusive of debt assumption
- Debt assumption: at least $785 million, backstopped by a 364-day senior secured bridge term loan from Barclays Bank PLC for up to $785 million
- Acquired asset: Long Ridge Energy & Power LLC, including a 505 MW combined-cycle gas plant in Hannibal, Ohio, plus 1,600+ contiguous acres of land
- Capacity impact: MARA’s owned-and-operated power capacity rises by approximately 65% to roughly 2.2 gigawatts
- Financial impact: approximately $144 million of annualized adjusted EBITDA (based on Long Ridge’s 2H 2025 performance)
- Closing conditions: Hart-Scott-Rodino Act clearance and Federal Energy Regulatory Commission approval; expected to close in Q3 2026 per FTAI Infrastructure’s 8-K disclosure
A 2.2 gigawatt operator is not a junior power consumer. It is in the same order of magnitude as the energy footprints public hyperscalers and digital infrastructure REITs disclose in their own 10-Ks. The 8-K is, functionally, MARA’s notice that it intends to be priced against that comparable set.
The Hannibal Site Is the Story Underneath the Headline
The 505 MW Hannibal asset is not a generic fleet addition. It is a behind-the-meter combined-cycle gas plant in the PJM interconnection, paired with on-site land for a digital infrastructure campus. The 8-K and MARA’s investor materials describe a path to up to 600 gross MW at the site over time, through a combination of grid expansions and additional on-site generation. The first AI/Critical IT buildout is targeted to begin construction in 1H 2027 and to be ready for service in mid-2028.
That timeline is the single most important thing the press release tells the model:
- 2026: close the deal, integrate, advance permitting.
- 2027: start vertical buildout for AI/Critical IT tenants.
- 2028: initial capacity in service, lined up against potential investment-grade tenant interest the company has already disclosed receiving.
A bitcoin miner does not pay $1.5 billion for an Ohio combined-cycle gas plant on a 2026–2028 buildout schedule unless the asset thesis has shifted from compute-for-mining to compute-for-anyone-who-pays-for-power. The schedule is the thesis.
The Seller’s 8-K Confirms the Other Side of the Trade
The cleanest validation that this is a closed-perimeter, two-sided transaction is the FTAI Infrastructure 8-K filed the same day, on the same EDGAR window, on the seller side of the table:
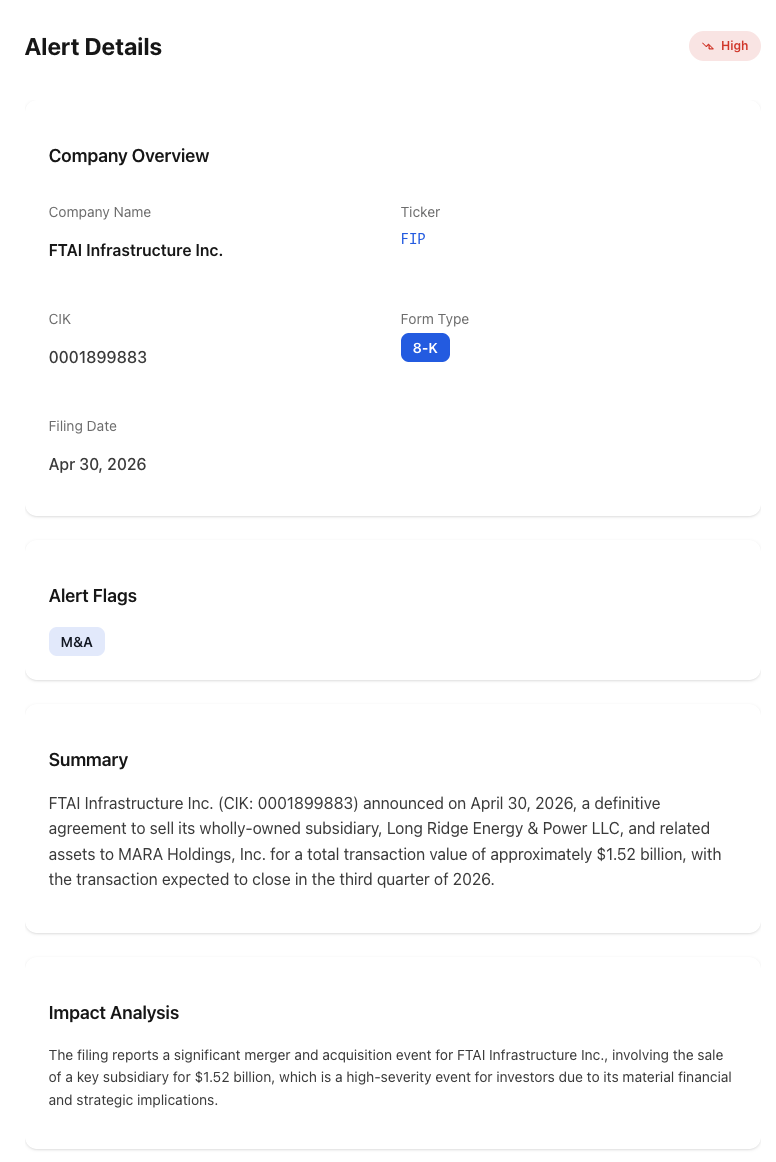
- Form: 8-K
- Filer: FTAI Infrastructure Inc. (CIK 0001899883, NASDAQ:
FIP) - Severity: High
- Flag: M&A
- Filing date: April 30, 2026
- Disclosure: definitive agreement to sell its wholly-owned subsidiary, Long Ridge Energy & Power LLC, and related assets, to MARA Holdings, Inc. for a total transaction value of approximately $1.52 billion
- Expected closing: Q3 2026
Two-sided same-day 8-K disclosures matter for three reasons:
- Price confirmation. Both filings reference compatible value figures — MARA discloses a $1.5B base purchase price; FTAI discloses a $1.52B total transaction value. The delta is the assumed debt and customary adjustments. Symmetrical disclosure is the strongest filings-level evidence that the price is a fixed number, not a moving target.
- Closing date sharpening. MARA’s 8-K guides “second half of 2026.” FTAI’s 8-K narrows that to Q3 2026. Sellers typically have less optionality on closing language than buyers — they need the cash. The Q3 framing is the operative one for anyone modeling FTAI’s deleveraging or MARA’s bridge-to-permanent-financing path.
- Counterparty identification. Reading buyer-side filings without the matching seller-side filing leaves Ohio River Partners as a name without a public ticker. The FTAI 8-K confirms the seller-side public obligor and the cashtag pair (
MARA/FIP) that the sell-side note will run.
The Same-Day DEF 14A Is the Third Document on the Stack
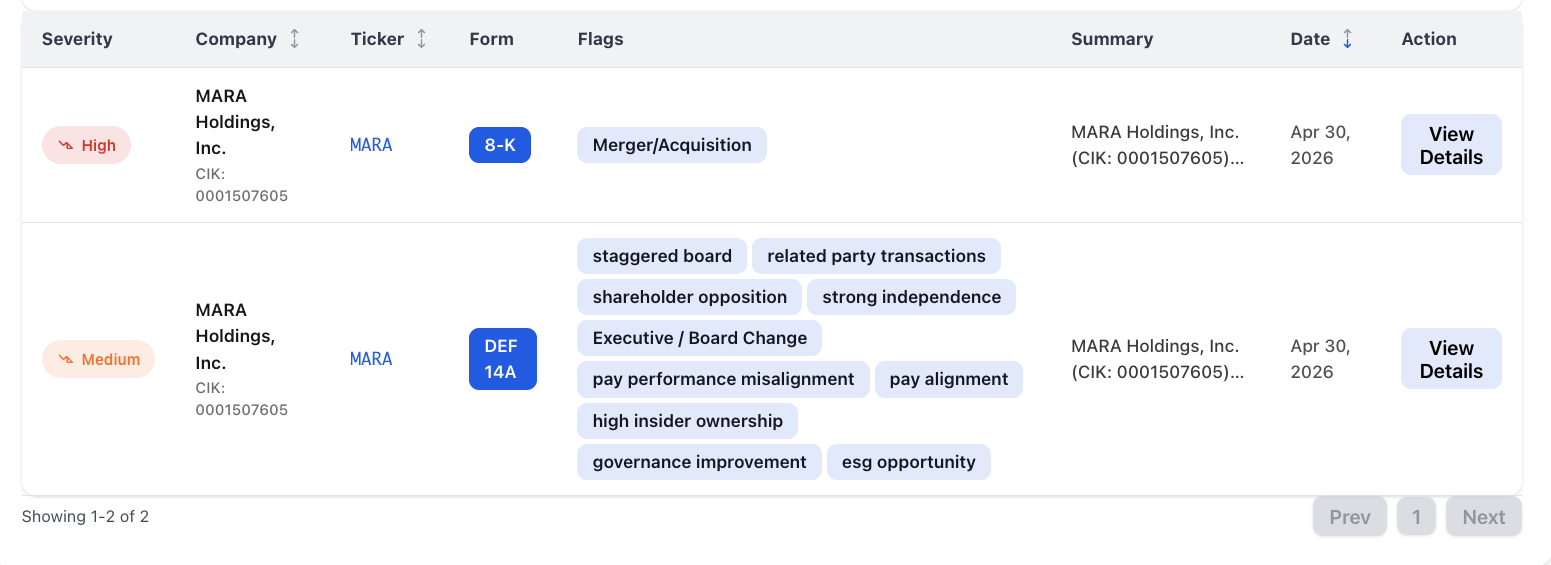
NexusAlert classified the 8-K as High-severity Risk with a Merger/Acquisition flag. It classified the DEF 14A — filed the same day — as Medium-severity with ten flags: staggered board, related party transactions, shareholder opposition, strong independence, board refreshment, pay performance misalignment, pay alignment, high insider ownership, governance improvement, and esg opportunity.
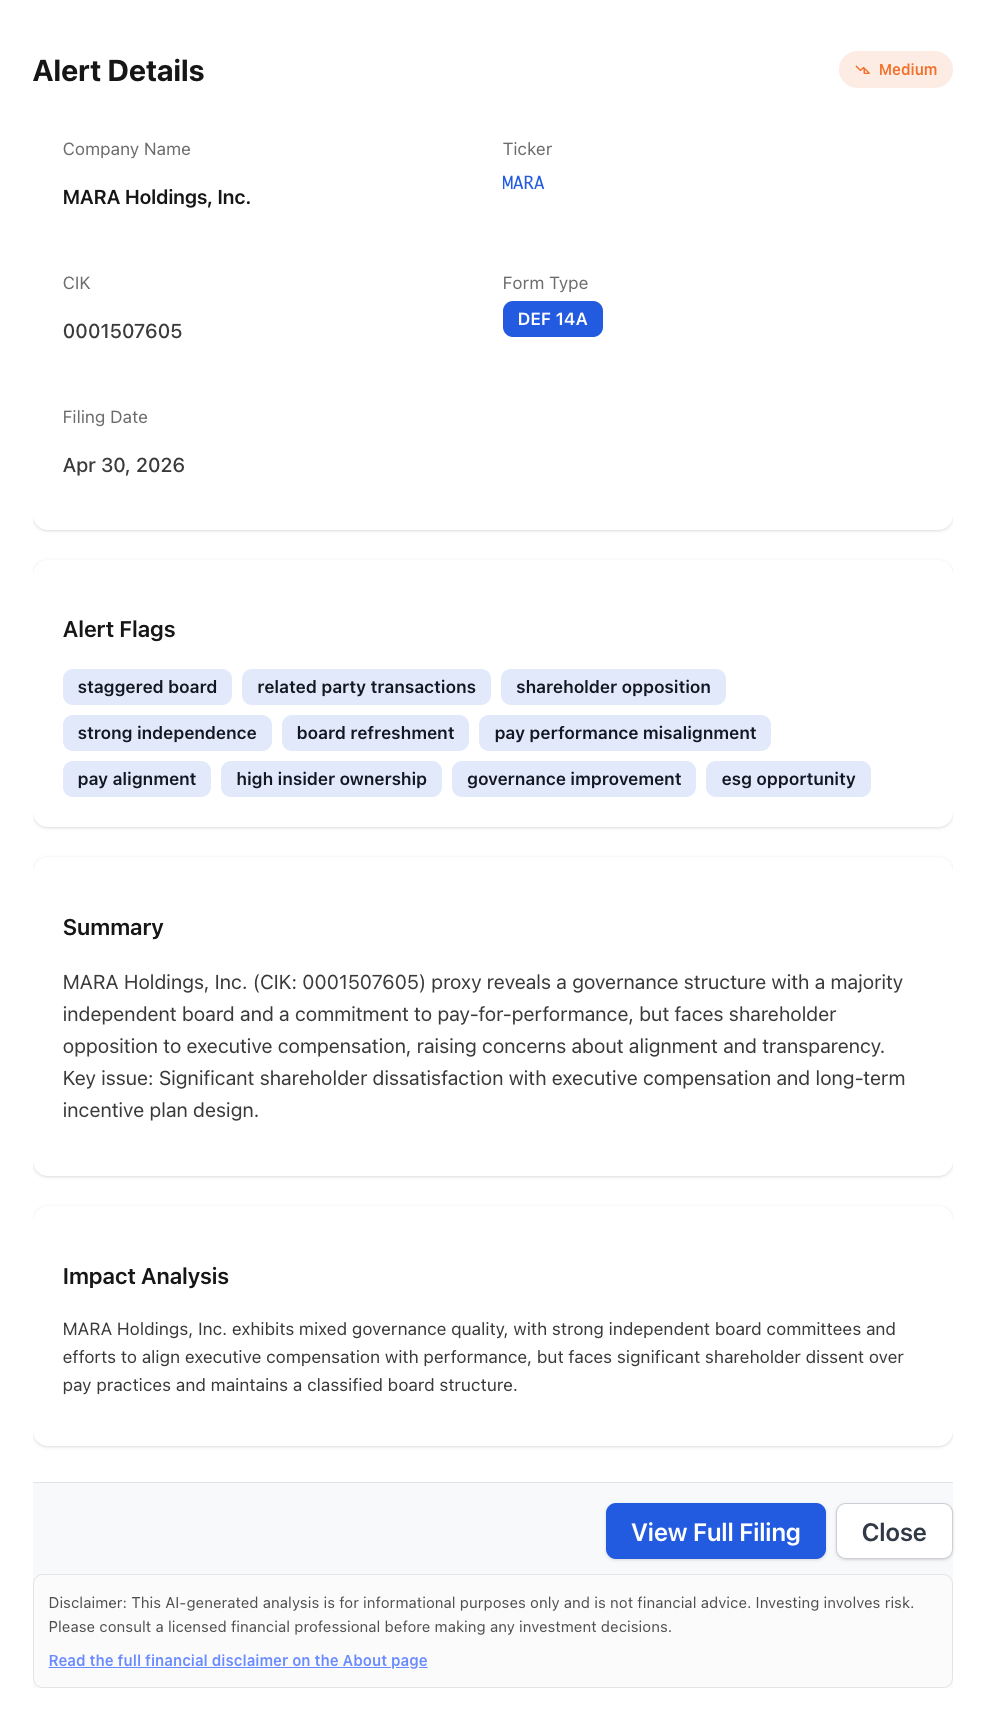
Ten flags on a single proxy is not noise. It is a structured read of a governance document that contains both ownership-quality signals and unresolved investor concerns:
- Board independence: 6 of 7 directors independent; all five standing committees (Risk and Audit, Talent, Culture and Compensation, Nominating and Corporate Governance, Social Responsibility, Technology and Strategy) are 100% independent. Douglas Mellinger serves as Lead Independent Director with defined responsibilities.
- Classified board: the company maintains a staggered board structure, which limits annual director accountability and slows board refreshment.
- 2025 say-on-pay: the prior year’s advisory vote received approximately 21.6% support — roughly 20.2 million votes for against 73.2 million votes against. That is a failed advisory vote on executive compensation by any reasonable definition.
- 2026 compensation overhaul: in response, the company is replacing Hashrate Hours with OpEx per MWh as the core performance metric for annual cash bonuses, extending the relative TSR performance period for LTIP awards to three years, and increasing the rigor of PSU payouts (now requiring the 55th percentile relative to the Russell 2000 for target payout).
- Plan share request: the board recommends amending the 2018 Plan to increase the share reserve by 18 million (from 63 million to 81 million), citing a 75% increase in employee headcount from 2024 to 2025 as a driver.
- Related-party transaction: as of December 31, 2025, MARA’s total investment in Auradine, Inc. was $85.4 million, with $136.7 million in advanced payments for product purchases in 2025. CEO Fred Thiel holds a board seat at Auradine. The Audit/Risk Committee oversees related-party transactions with independence standards.
- Executive compensation: Fred Thiel’s 2025 total compensation in the Summary Compensation Table was $27,053,236, while his “compensation actually paid” was $6,229,101 — a substantial gap explained by the equity-marking conventions of the rule. Average non-PEO NEO total comp was $12,501,550 with comp actually paid at $3,658,345.
A failed say-on-pay vote, a classified board, a renamed bonus metric, an 18-million-share plan increase, and a $222M-cumulative related-party arrangement do not summarize as “MARA filed a proxy.” They summarize as “the proxy is the document.”
Why Three Filings, One Day, Two Tickers Is the Showcase
A multi-filing event spanning two tickers on a single trading day is exactly the scenario filings detection is built for. Each filing alone would be a clean alert. Together, they are a coordinated capital-markets event:
- MARA’s 8-K shifts the buyer’s asset base from compute-for-mining to compute-for-AI-tenants.
- FTAI’s 8-K confirms the seller-side mark and the Q3 2026 closing window the deleveraging story rides on.
- MARA’s DEF 14A shifts the buyer’s equity story by conceding 2025’s compensation design and replacing the bonus metric most associated with the legacy mining identity (Hashrate Hours) with one tied to operational efficiency across the broader infrastructure base (OpEx per MWh).
The metric change is itself a tell. A company that intends to be priced as an AI infrastructure operator does not pay its NEOs on a hashrate output measure. It pays them on a power-cost efficiency measure. The proxy is signaling alignment with the same thesis the 8-K is announcing in dollars.
What the Investor Trends Data Says About Who Is Selling
NexusAlert’s Investor Trends view for MARA over the trailing six months — pulled the morning after these filings — surfaces a separate signal worth reading alongside the document set:
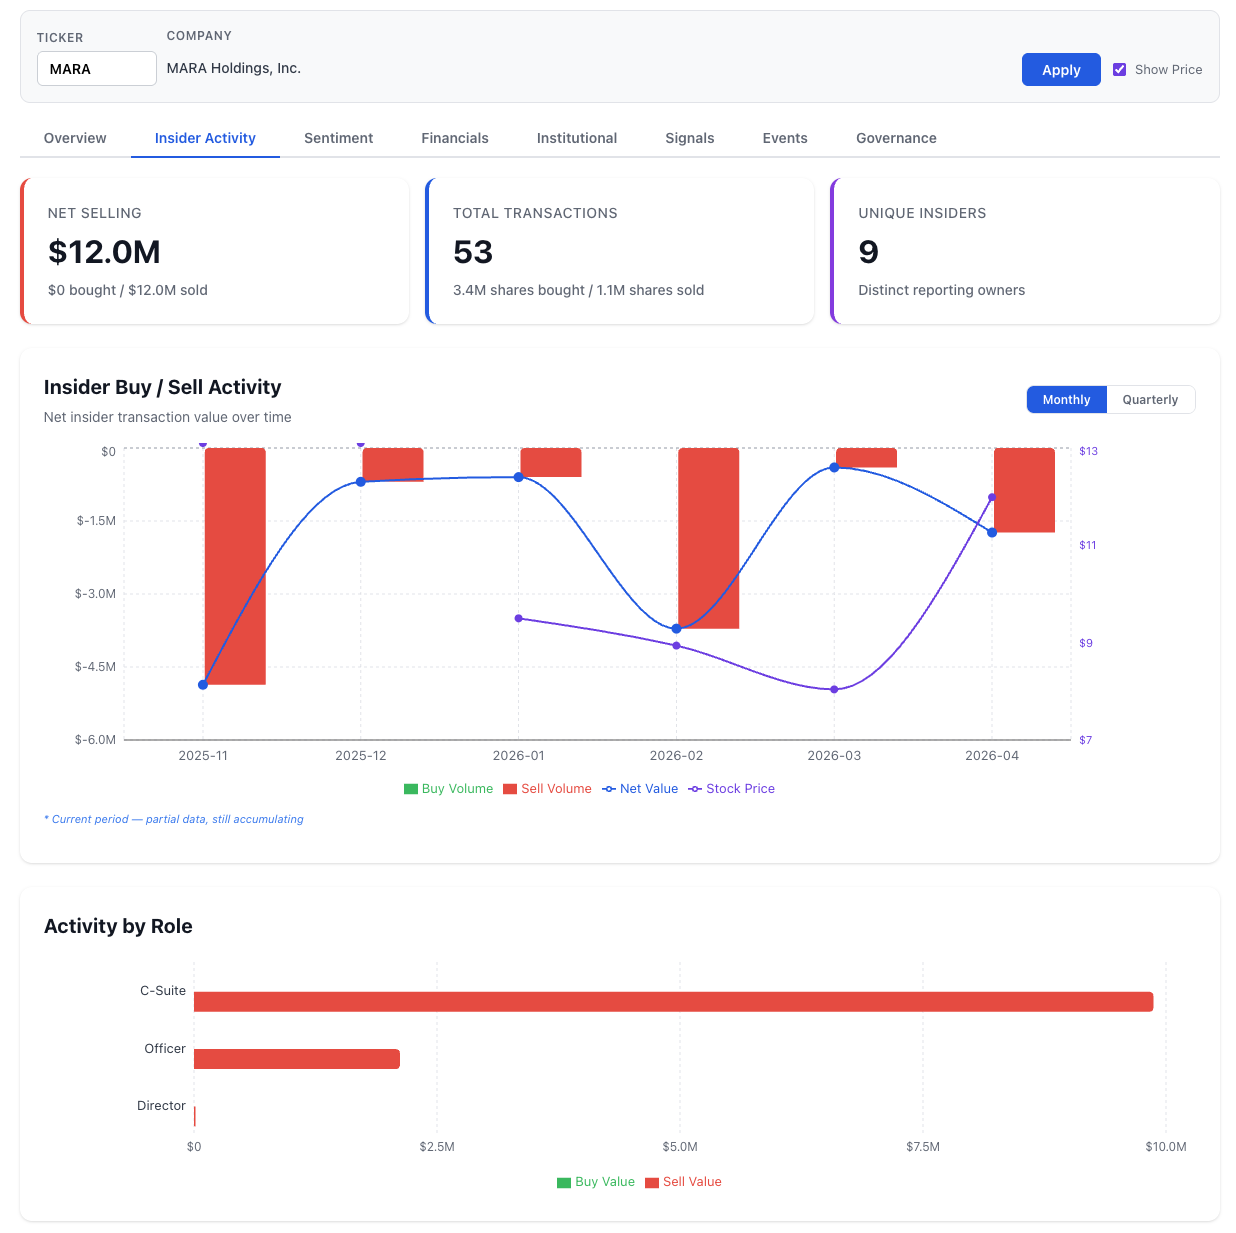
- Net selling: $12.0 million ($0 bought / $12.0 million sold)
- Total transactions: 53 across 9 unique insiders
- Activity by role: C-Suite leads sell volume by a wide margin
- Most frequent flags: Large Sale, Routine Sale, Ownership Decrease — alongside Ownership Increase and 10b5-1 Plan markers
- Institutional holders: 31 with $3.5 billion in total institutional value, and 26 new positions opened during the period
- SC 13D/13G filers: 3 — all passive (zero activist)
Two takeaways:
- The insider-side activity is one-directional: zero open-market insider buys during the trailing window, $12M of insider sales, with C-Suite leading the volume. Most of those sales are flagged as Large Sale or Routine Sale (consistent with 10b5-1 trading plans), not panic selling — but the absence of any open-market insider buy at the same time the company is staking $1.5B on a long-dated infrastructure thesis is itself a data point analysts will mark.
- The institutional side is constructive: a $3.5B institutional book with 26 fresh positions and three passive 13D/13G filers means index, factor, and passive money is flowing in around the strategic pivot, even before the deal closes.
That mix — insiders not buying on news, passives building positions, the company filing a 10-flag governance proxy — is exactly the kind of sentiment-and-flow read that the Investor Trends layer over a single ticker is designed to surface.
What Happens in the Next Three Filings
The 8-K is the announcement. The DEF 14A is the governance pivot. The disclosures that move the model are downstream:
- The next 10-Q will show purchase accounting around the closing date, the new energy segment’s contribution, the depreciation policy on combined-cycle generation assets, and any updated leverage ratios reflecting the assumed Long Ridge debt and the Barclays bridge facility.
- HSR and FERC filings will set the regulatory clock. FERC approval in particular will be the lever for any conditions on the change-of-control of the 505 MW generator.
- The next 10-K will require a Risk Factors update reflecting natural-gas commodity exposure, environmental and regulatory risk on the Ohio asset, and customer concentration risk on whatever AI/HPC tenants Long Ridge or MARA bring under contract.
- The 2026 say-on-pay vote at the upcoming annual meeting will be the live test of whether the OpEx-per-MWh / 3-year TSR / 55th-percentile-Russell-2000 reset is enough to win back the holders who voted against in 2025.
- Any 8-K announcing a tenant agreement at Hannibal — particularly an investment-grade AI counterparty — will be the most market-moving filing event of the multi-quarter integration window.
Why Multi-Filing, Multi-Ticker Tracking Is the Workflow
Most automated wire systems summarize April 30, 2026 as “MARA Holdings to buy Long Ridge Energy in $1.5 billion AI data center push.” That summary is correct, and it misses the rest of the day’s filings entirely. EDGAR carried three documents anchoring the same event:
- MARA 8-K — M&A definitive agreement, M&A flag, High severity.
- MARA DEF 14A — proxy, ten governance flags, Medium severity.
- FTAI Infrastructure 8-K — seller-side disposition, M&A flag, High severity.
A watchlist tuned to MARA gets two of the three within minutes of EDGAR posting. A watchlist tuned to FIP gets the third. A semantic search across 8-K, DEF 14A, 10-K, 10-Q, and Form 4 flow stitches all three together — surfacing the buyer-side and seller-side disclosures, the prior-year say-on-pay result the proxy is responding to, the Auradine related-party history across multiple proxies, and the Form 4 selling pattern the Investor Trends panel aggregates.
That stitching is the difference between reading a wire headline and reading a company.
Track Same-Day, Multi-Ticker Filing Events as They Land
Create a free NexusAlert account to get real-time alerts on 8-K acquisitions from both sides of the trade, DEF 14A governance flags, and same-day multi-filing events across every public ticker — with the deal terms, counterparty identification, related-party details, and prior-year vote results parsed straight from the filings.
$MARA $FIP
Sources
- MARA Advances Its Optimized Digital Infrastructure Strategy with Agreement to Acquire Long Ridge Energy & Power — MARA investor relations
- FTAI Infrastructure Inc. Announces Agreement to Sell Long Ridge Energy and Power to MARA Holdings, Inc. — GlobeNewswire
- FTAI targets debt cuts in $1.52B Long Ridge sale to MARA — StockTitan
- MARA Holdings to buy Long Ridge Energy in $1.5 billion AI data center push — CoinDesk
- MARA to Acquire Long Ridge Energy for $1.5 Billion; Secures $785 Million Bridge From Barclays — TradingView
- MARA agrees to acquire Long Ridge Energy for $1.5bn — Power Technology
- MARA (NASDAQ: MARA) plans $1.5B Long Ridge Energy acquisition to boost capacity — StockTitan
- Bitcoin miner MARA to acquire Long Ridge in $1.5 billion Ohio gas plant deal — The Block
- MARA Holdings, Inc. SEC filings — EDGAR (CIK 0001507605)
Prefer to own it outright? NexusAlert lifetime access is available for a one-time payment of $299 — no subscription, no recurring charges, all future Pro features included. Learn more →