John Malone Just Gave Up Control of Liberty Media. He Did Not Sell.
Liberty Media swapped 2,316,537 of Malone's high-vote shares for about 6.0 million ordinary shares, cutting his voting power from about 48% to 3%. A poison pill went up the same day.
John Malone just gave up control of the company behind Formula 1. He did not sell it.
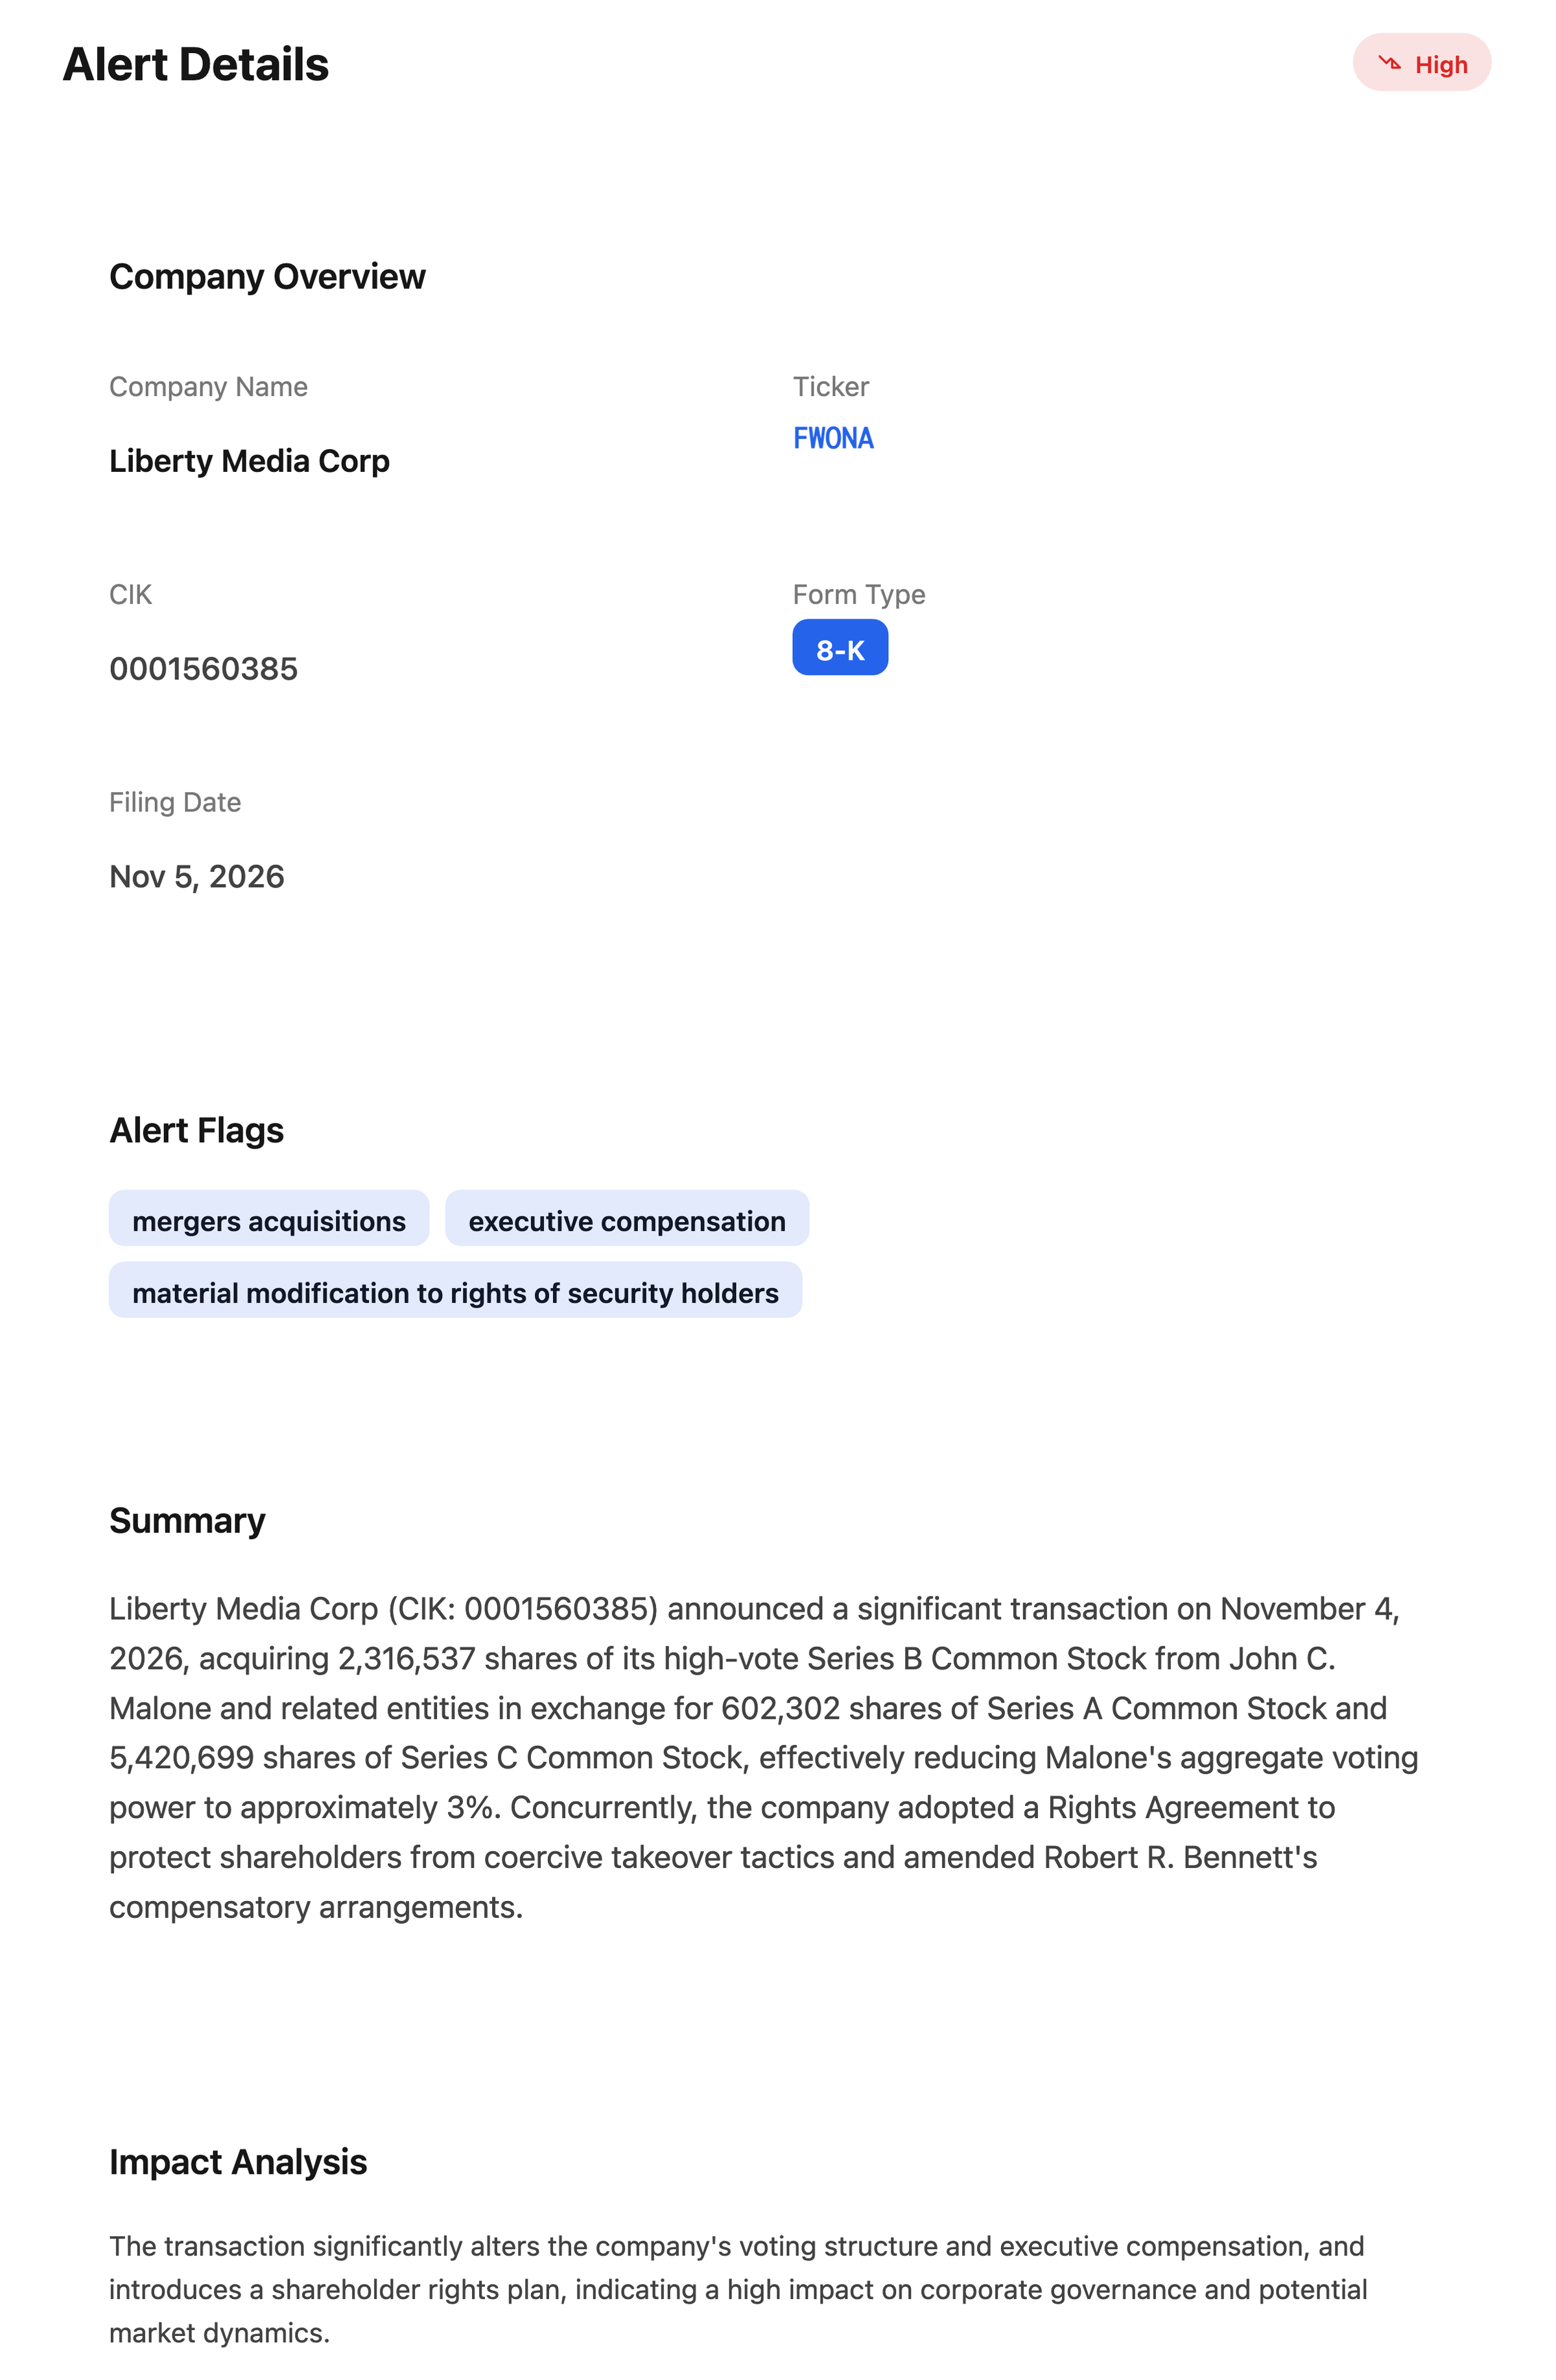
On November 4, 2026, $FWONA parent Liberty Media bought 2,316,537 high-vote Series B shares from John Malone and related entities. It paid in stock, not cash: 602,302 Series A shares and 5,420,699 Series C shares. According to Liberty’s press release, filed with the 8-K, Malone’s voting power fell from about 48% to about 3%. The Malone holders owned about 97% of the Series B stock, and all of it was exchanged.
So did the man who built much of modern cable media just cash out? Not the way the headline reads.
He swapped votes for shares, not shares for cash
Each Series B share became 0.26 Series A shares plus 2.34 Series C shares, or 2.6 ordinary shares for every high-vote share. The Series B shares were cancelled. Liberty puts the premium in that ratio at about 1.5% of its equity market value as of October 30.
Malone keeps a large economic stake and gives up the control. Liberty says the point is to line up his voting power with his economic ownership, and after the deal no holder has more than 9% of the vote. Malone also steps down as Chairman Emeritus and stays on as Senior Advisor.
That is a transfer of control, not an exit.
Someone had already bid for the vote
Liberty says the exchange followed unsolicited third-party offers for Malone’s Series B shares. A special committee chaired by director Chase Carey negotiated it, with the stated goal of keeping that voting block from landing in a third party’s hands.
Read that again. A high-vote block is an asset on its own, separate from the stock’s price, and an outsider had already shown up to buy it. Liberty’s answer was to buy the vote in house.
The poison pill went up the same day
The same 8-K adopts a Rights Agreement effective November 4, with a record date of November 16 and an expiration of November 3, 2027. It triggers at 10% of voting power, or 15% for a passive institutional investor. Cross the line without board approval and the rights let every other holder buy shares worth two times the exercise price of $426.00 per one ten-thousandth of a preferred share.
Is that good for shareholders? It can be. Ending a super-vote structure moves the company closer to one share, one vote, and Liberty says it may broaden its institutional investor base. It also leaves a company with no controlling holder and a pill that makes an unwanted bid harder, which gives the board more room to say no. Both readings fit the filing.
One filing, three stories
The 8-K runs eight items. Alongside the exchange and the pill, it amends Chairman Robert Bennett’s pay. His existing Series B options vest in full and are cancelled for cash. He gets new nonqualified options on 600,000 Series A shares and 60,000 Series C shares, vesting 20% at grant and 20% on each of the first four anniversaries.
A headline about Malone’s stake covers one of the three.
What the Dossier shows
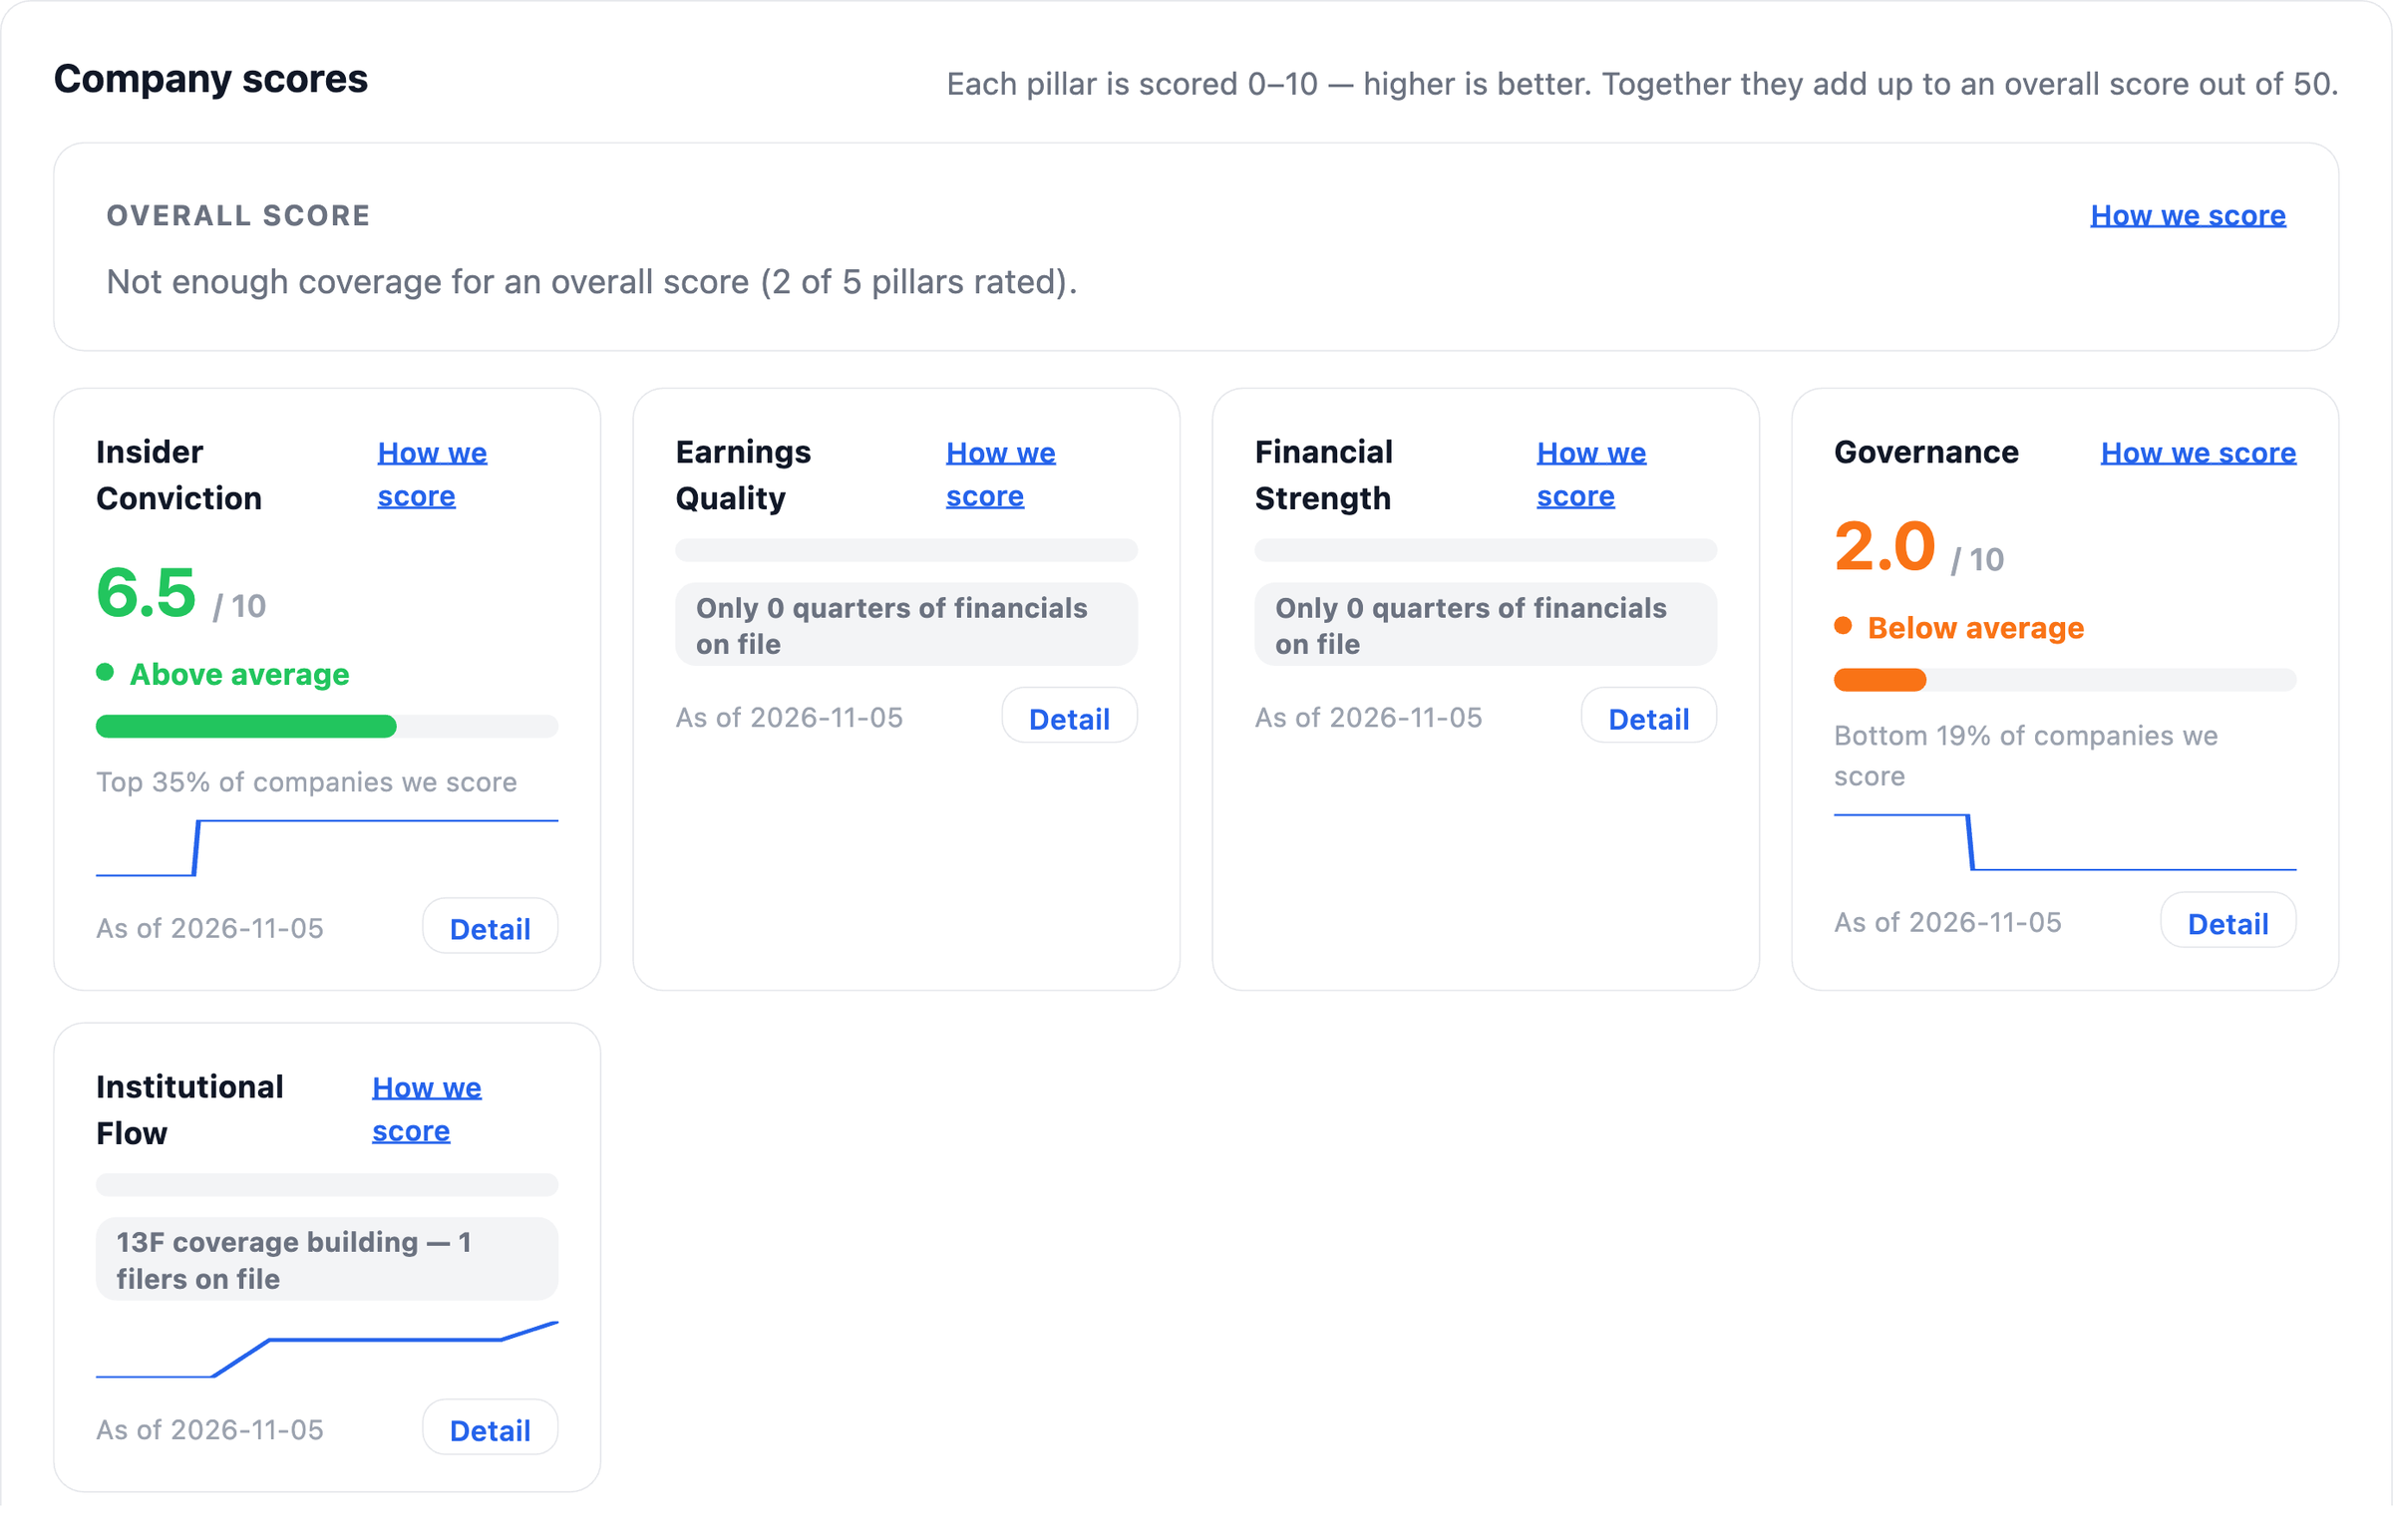
The Liberty Media Dossier scores Governance at 2.0 out of 10, in the bottom 19% of companies NexusAlert scores. Insider Conviction is 6.5, in the top 35%. Earnings Quality and Financial Strength are not rated because the Dossier has no quarters of financials on file for this ticker, so there is no overall score yet.
That is a thin coverage picture, and it is worth saying so. The governance pillar is the one to read next to this filing, since the filing rewrites who holds the vote.
Control is the one asset that never shows up in a share count.
NexusAlert flagged this 8-K the day it landed and put the exact share counts, the Rights Agreement and the Bennett amendment in one summary. The lesson travels to any stock: read the whole filing, not the headline.
Create a free NexusAlert account
Sources
Prefer to own it outright? NexusAlert lifetime access is available for a one-time payment of $299 — no subscription, no recurring charges, all future Pro features included. Learn more →